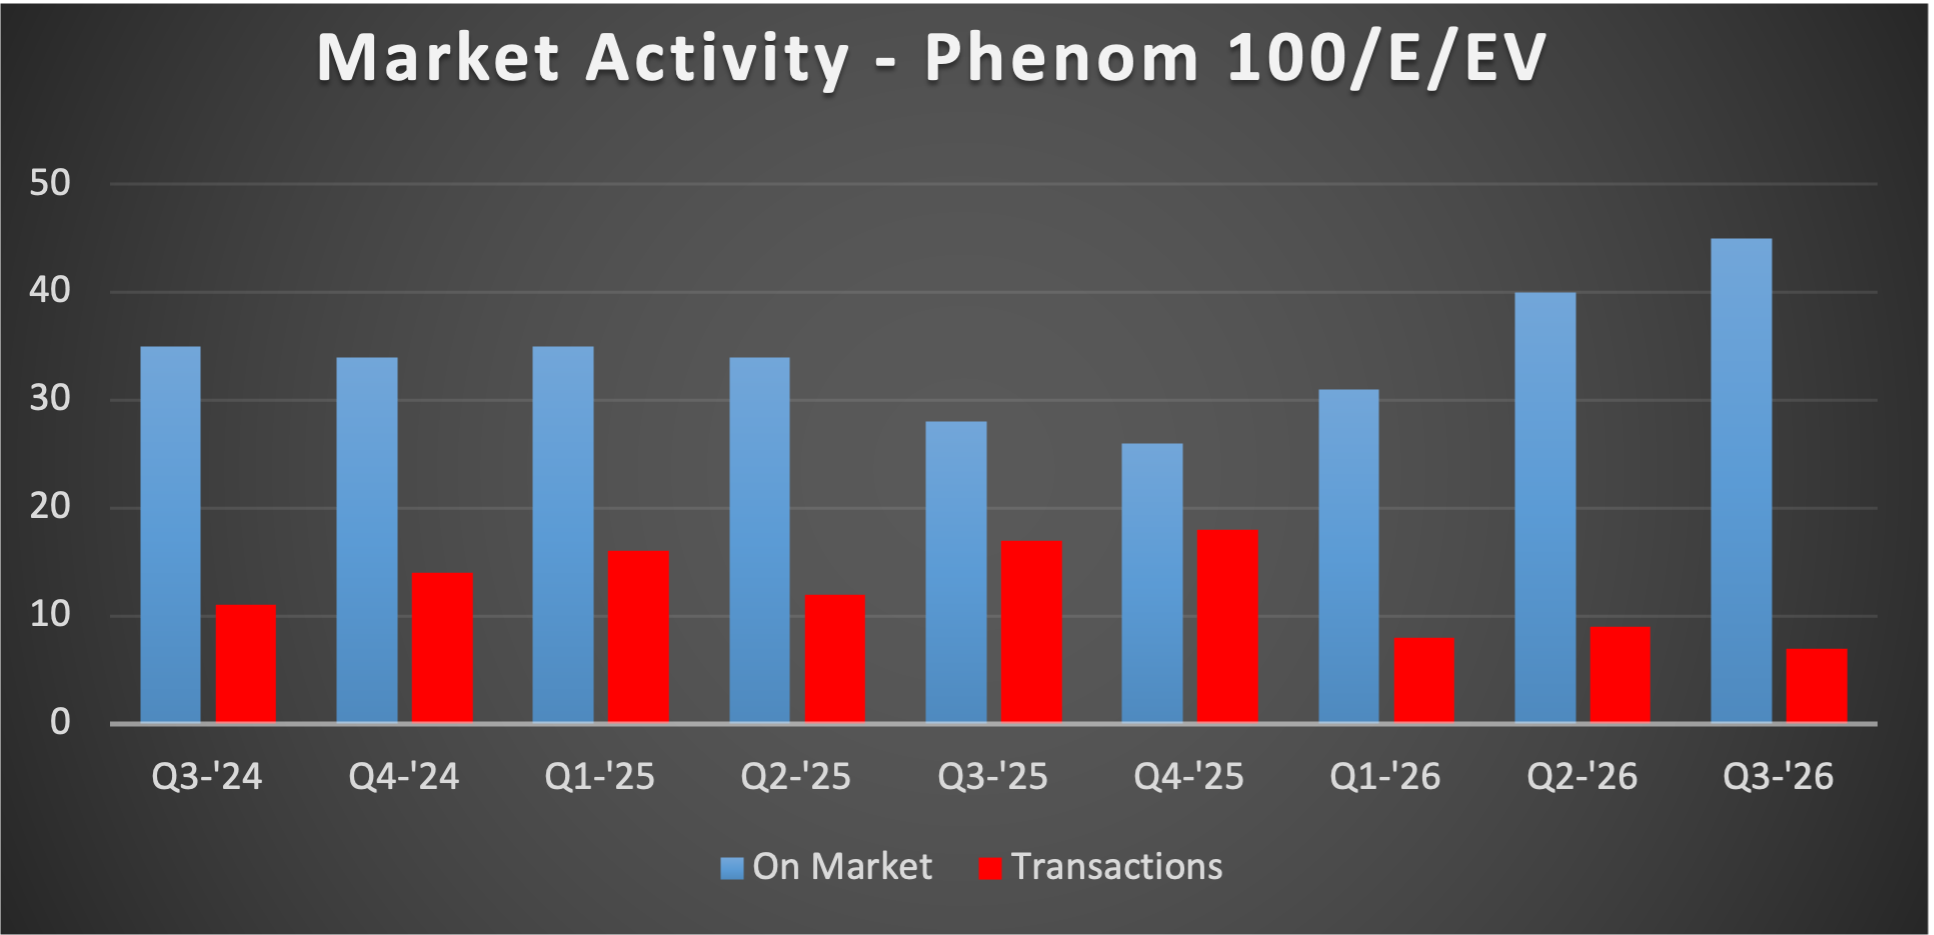
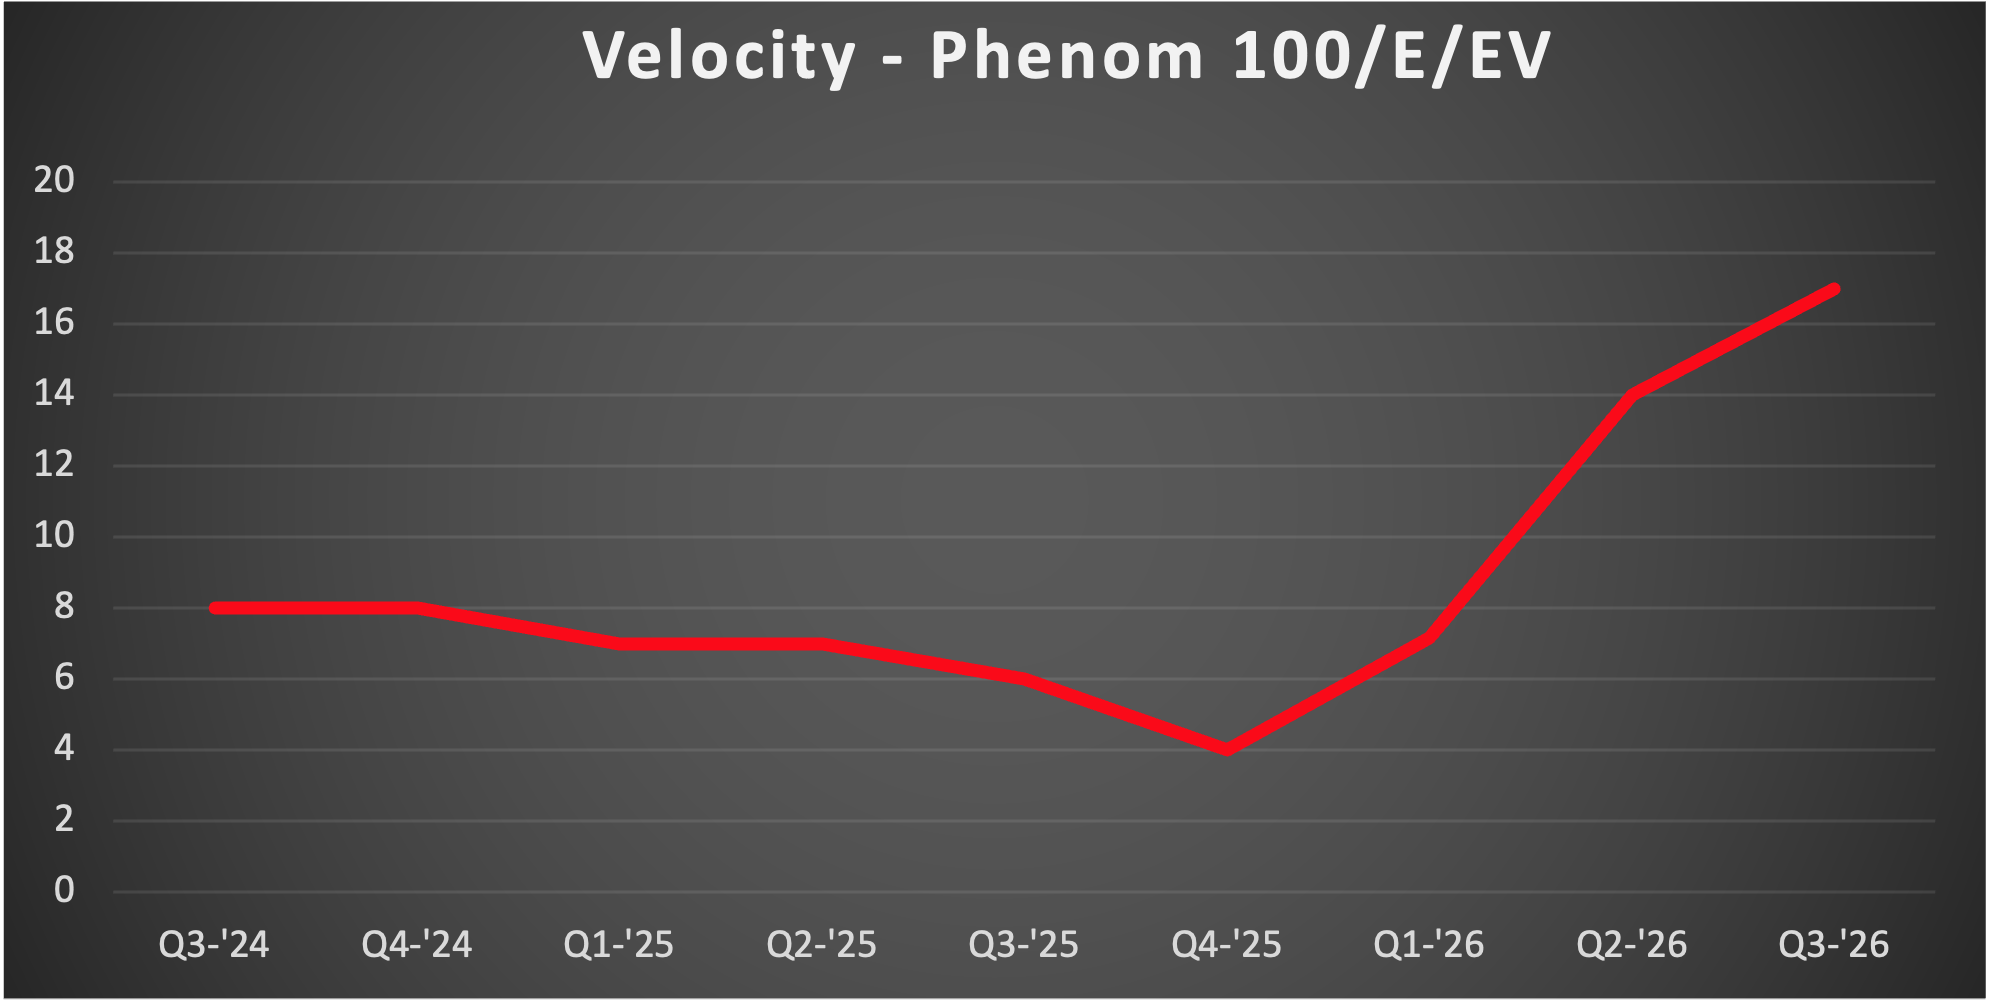
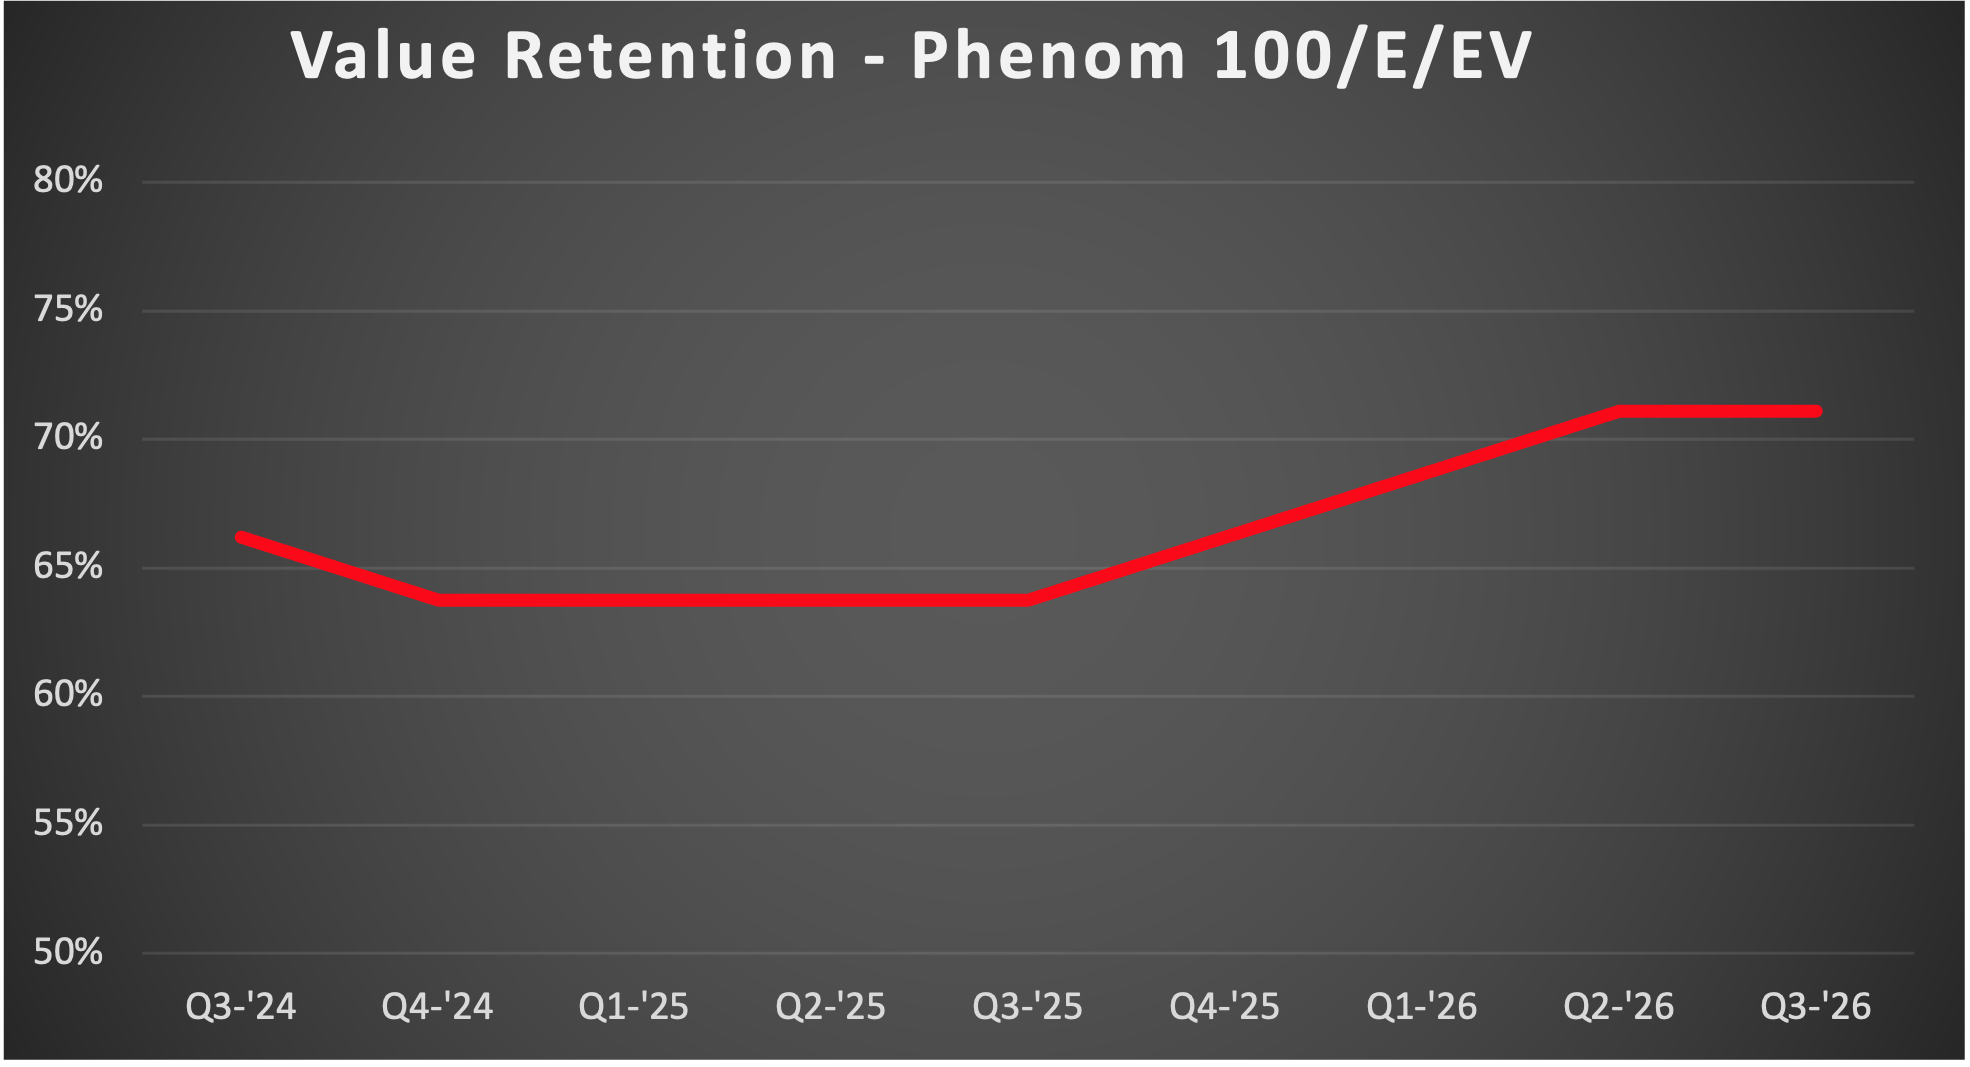
Inventory continues to rise in the Phenom 100 space, but values are holding steady. There are now 45 combined listings between the Phenom 100, 100E and 100EV markets, up from 40 last quarter and just 28 a year ago. Nearly 7% of the active fleet is listed, the highest level in many years. Activity has cooled off, with just seven sales taking place during Q3. This makes just 24 sales on the year, well behind last year’s pace of 45 transactions through Q3. Values remain strong, with late-model Phenom 100s bringing numbers as high as we’ve seen in recent years. Taking all this into consideration, early-model Phenom 100s are favorable for buyers, with later models holding stable as a balanced market.

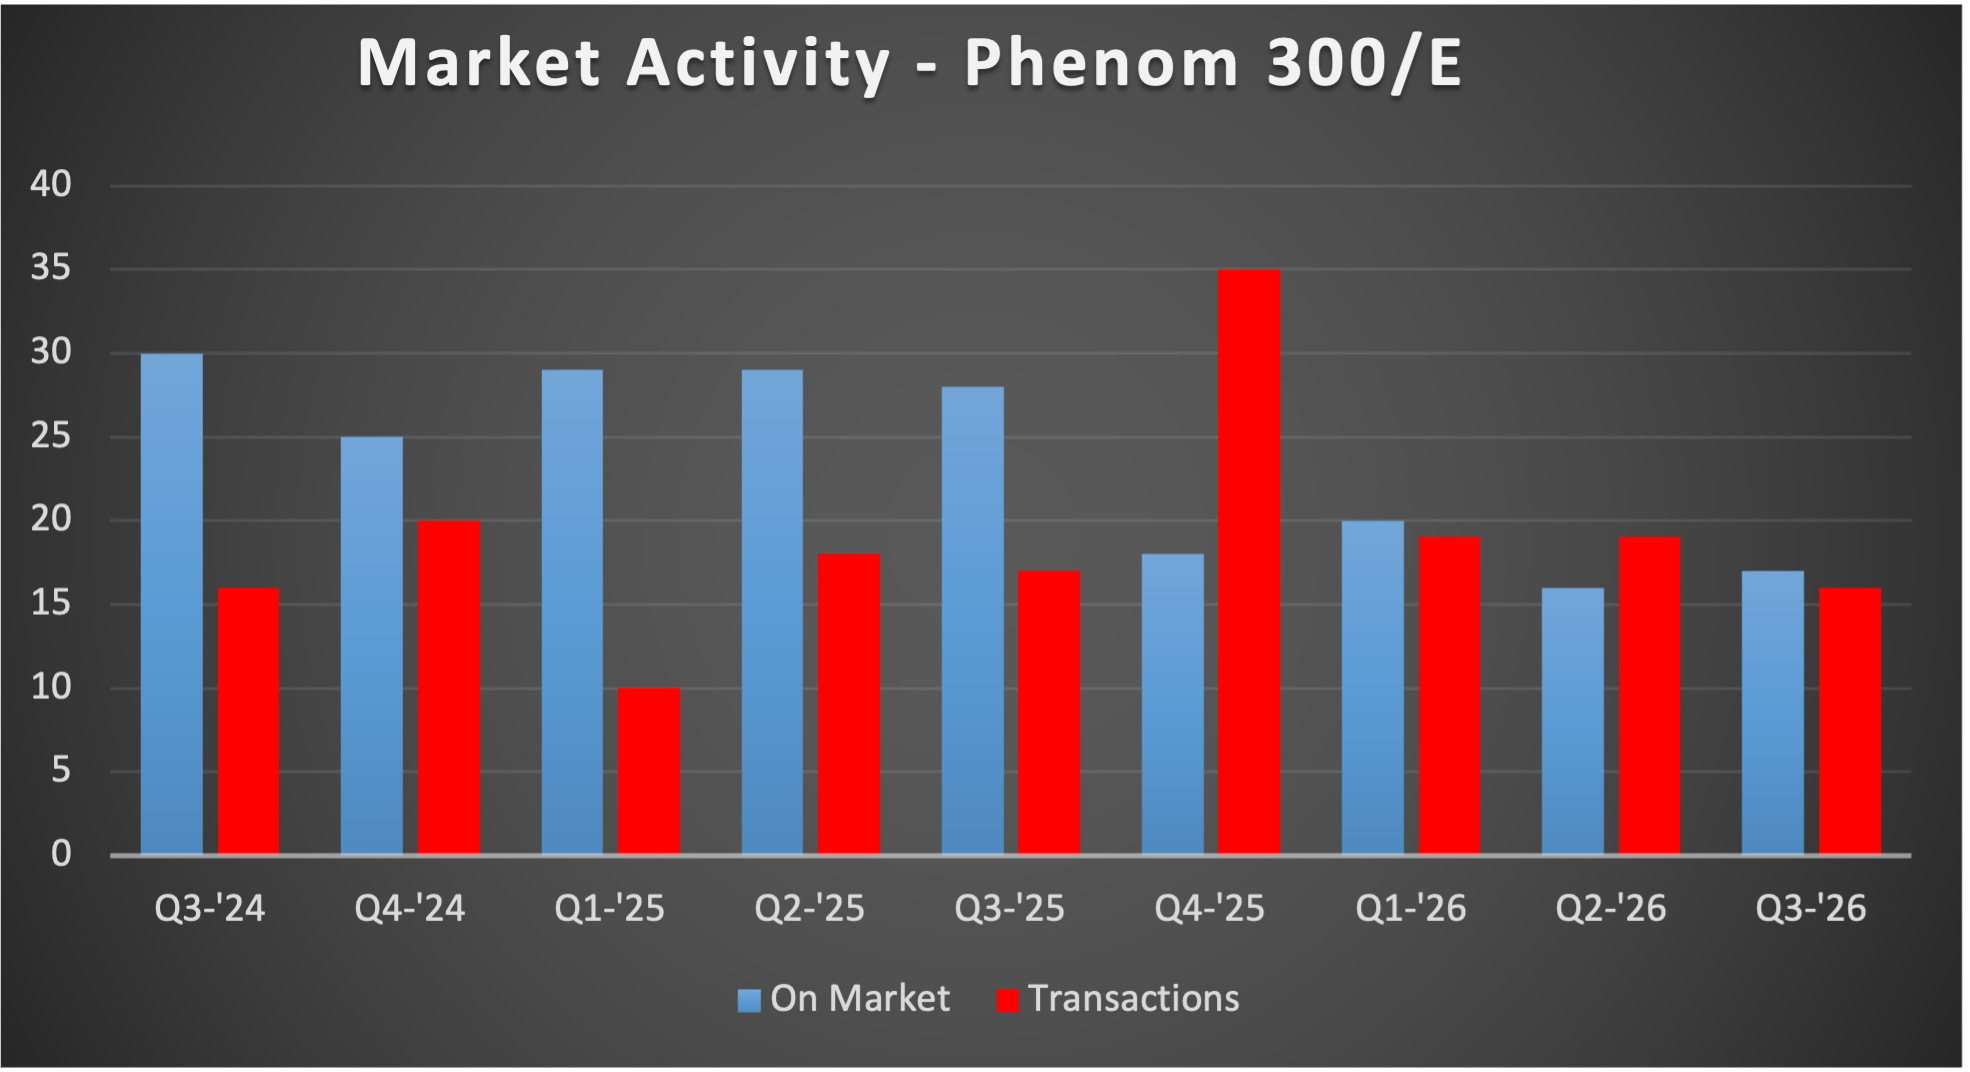
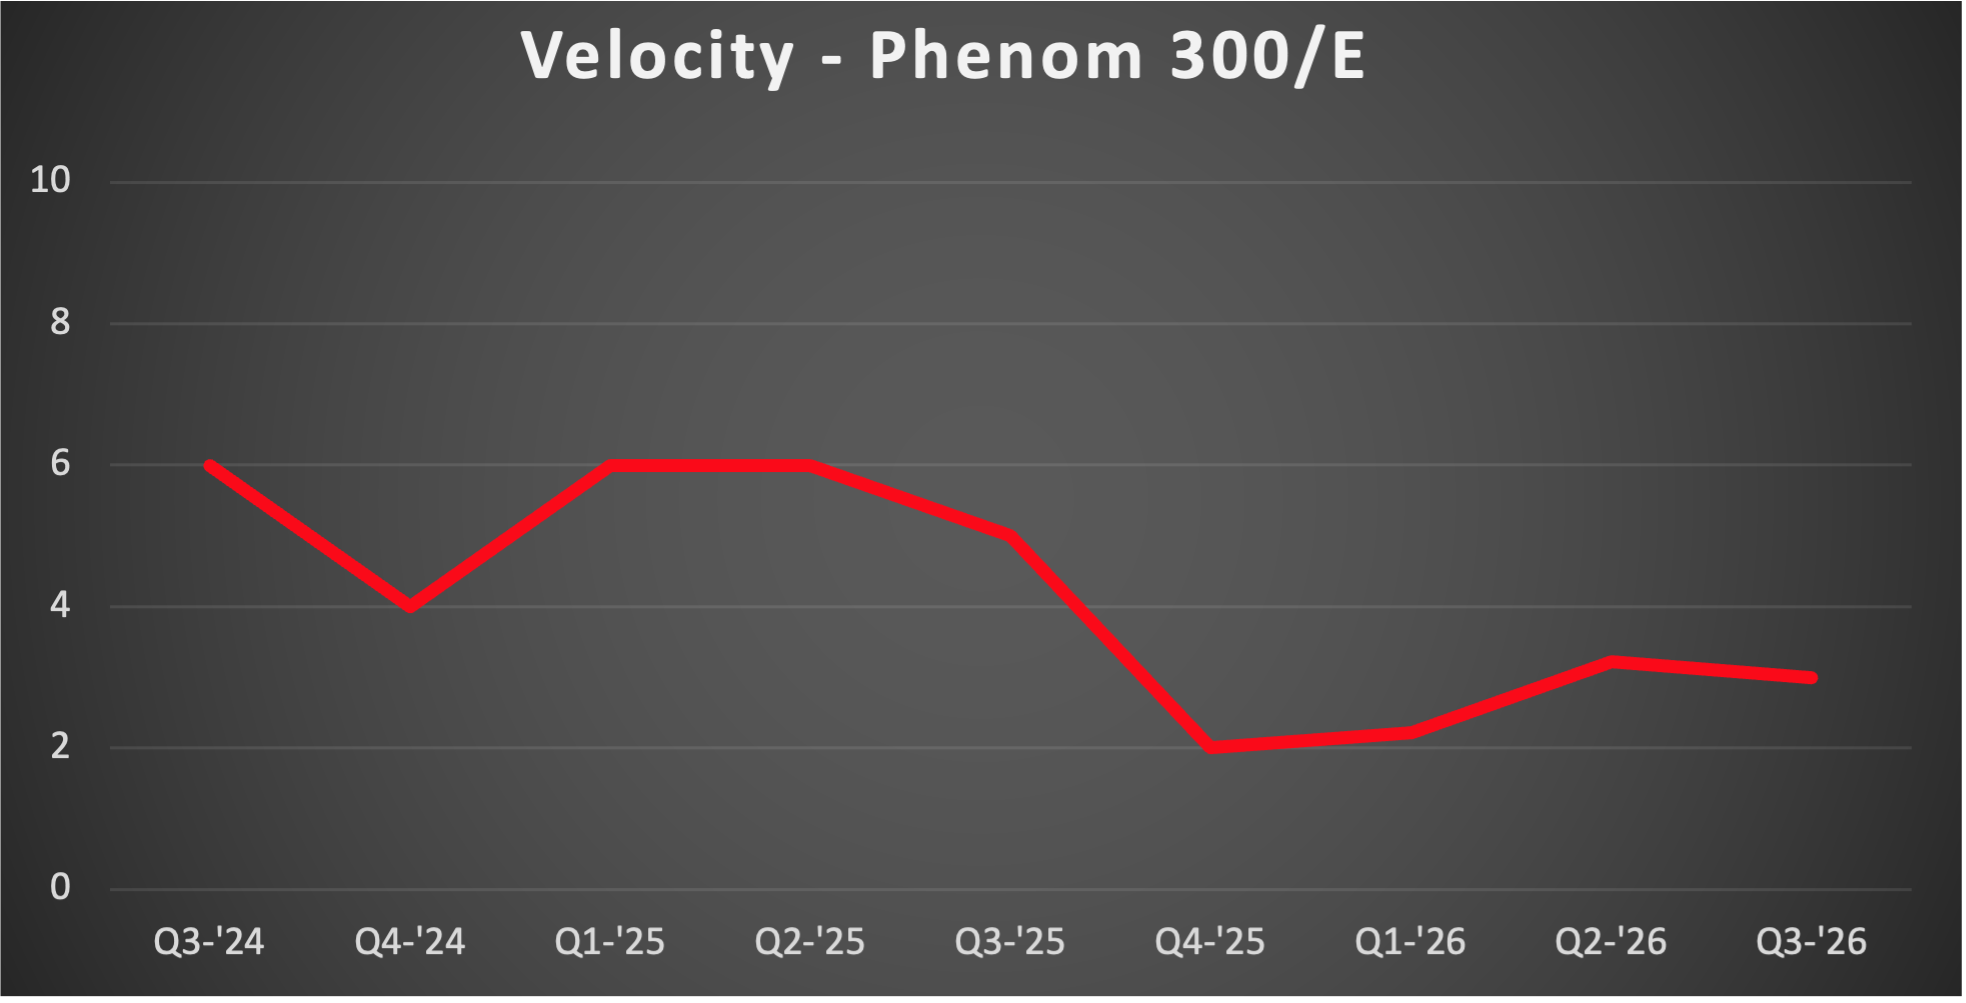
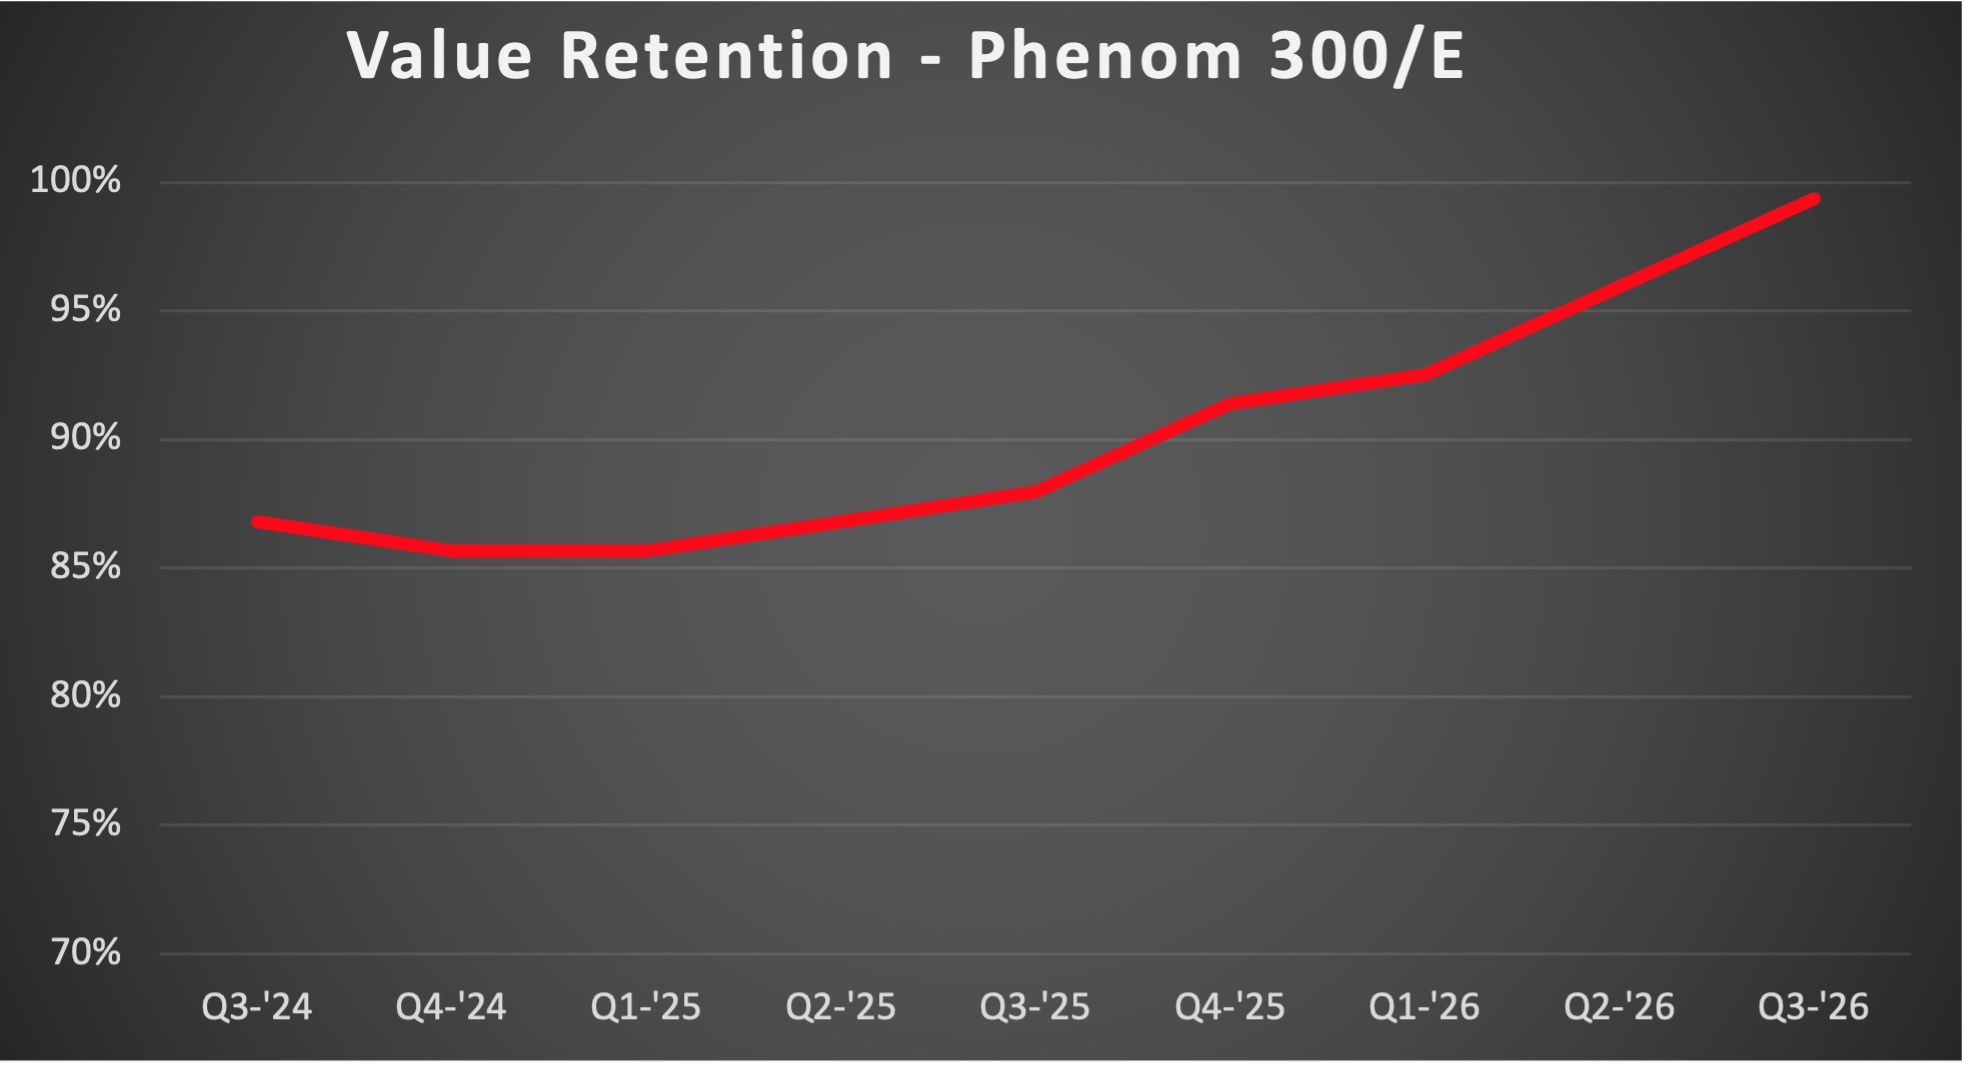
Phenom 300 and 300E inventory has leveled off, but at a historically low level. There are now 17 combined listings between these two markets, up just one from last quarter, but down from 28 listed a year ago. Under 2% of the active fleet remains for sale, which has buyers scrambling to find quality, US-based options. 16 aircraft sold during Q3, down slightly from last quarter, but in-line with Q3 of 2025. Values in the 300E and late model 300 space continue to be strong, with the G1000 Phenom 300’s surging more than $500k over the past few months. With the entire Phenom 300/300E space at historically high prices, this remains an incredible opportunity for sellers.


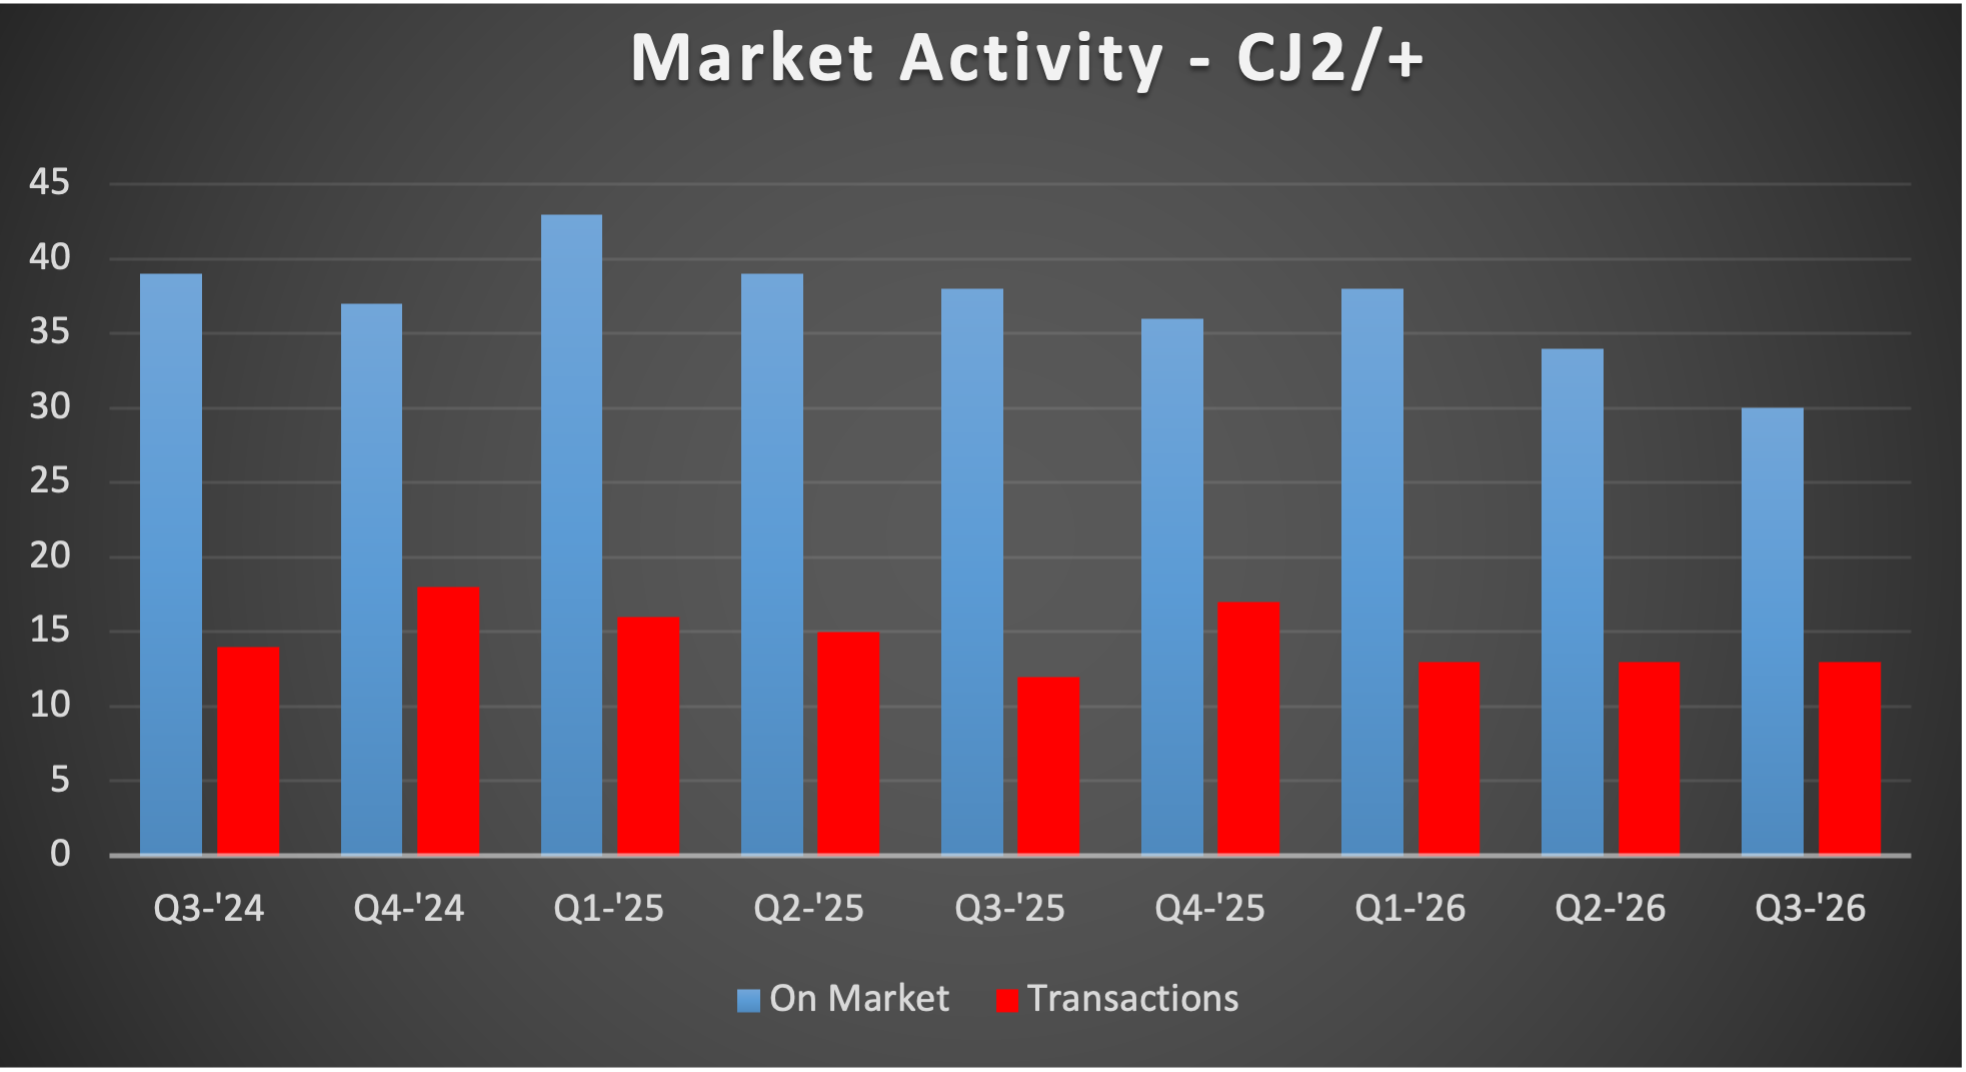
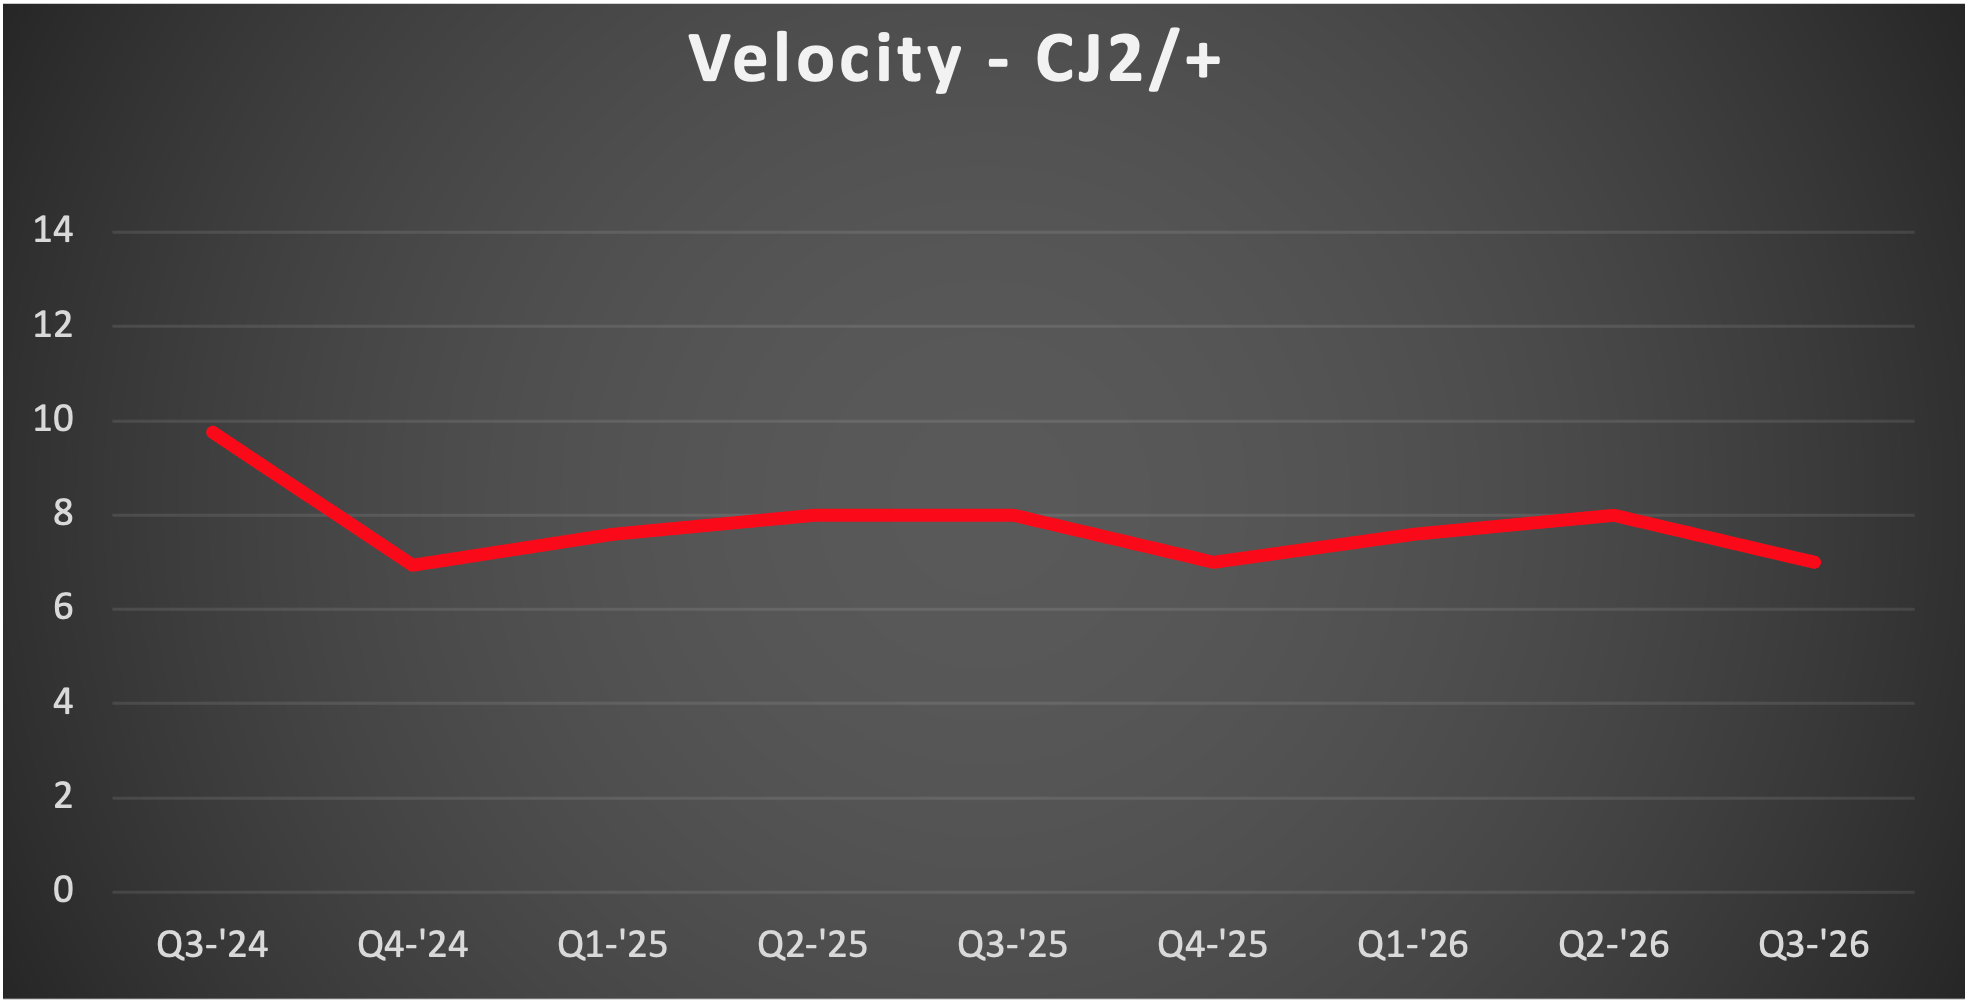
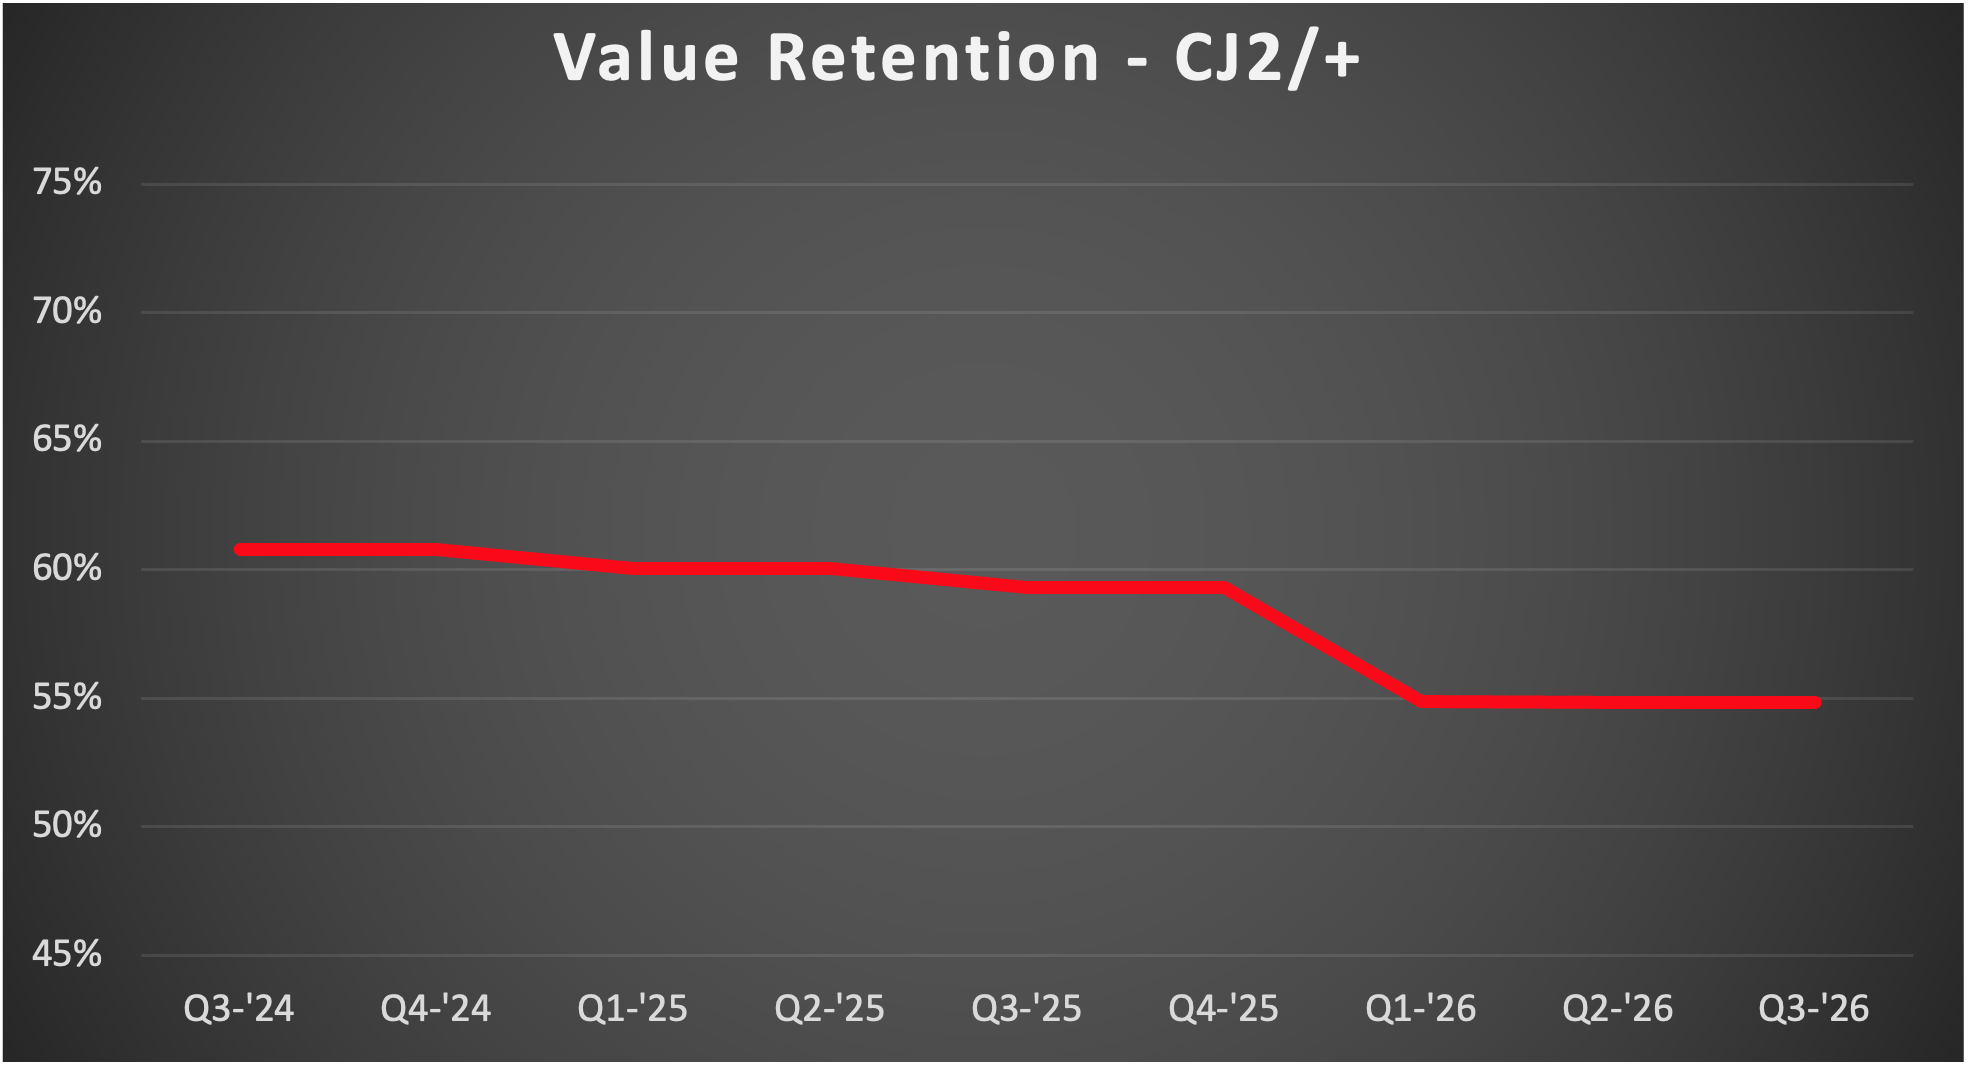
The CJ2 market held its ground for a second straight quarter following Q1's 7.5% correction. Values were flat, and transactions held at 13 for the third consecutive quarter. Average inventory continued to ease, falling from 34 to 30 aircraft, the lowest level since Q4 2023, which brought velocity down from nearly 8 months to just under 7. The improvement is coming from shrinking supply rather than rising demand. The market remains in buyers' territory, but conditions for sellers are slowly improving, and continued inventory declines could move the CJ2 back toward balanced in the quarters ahead.


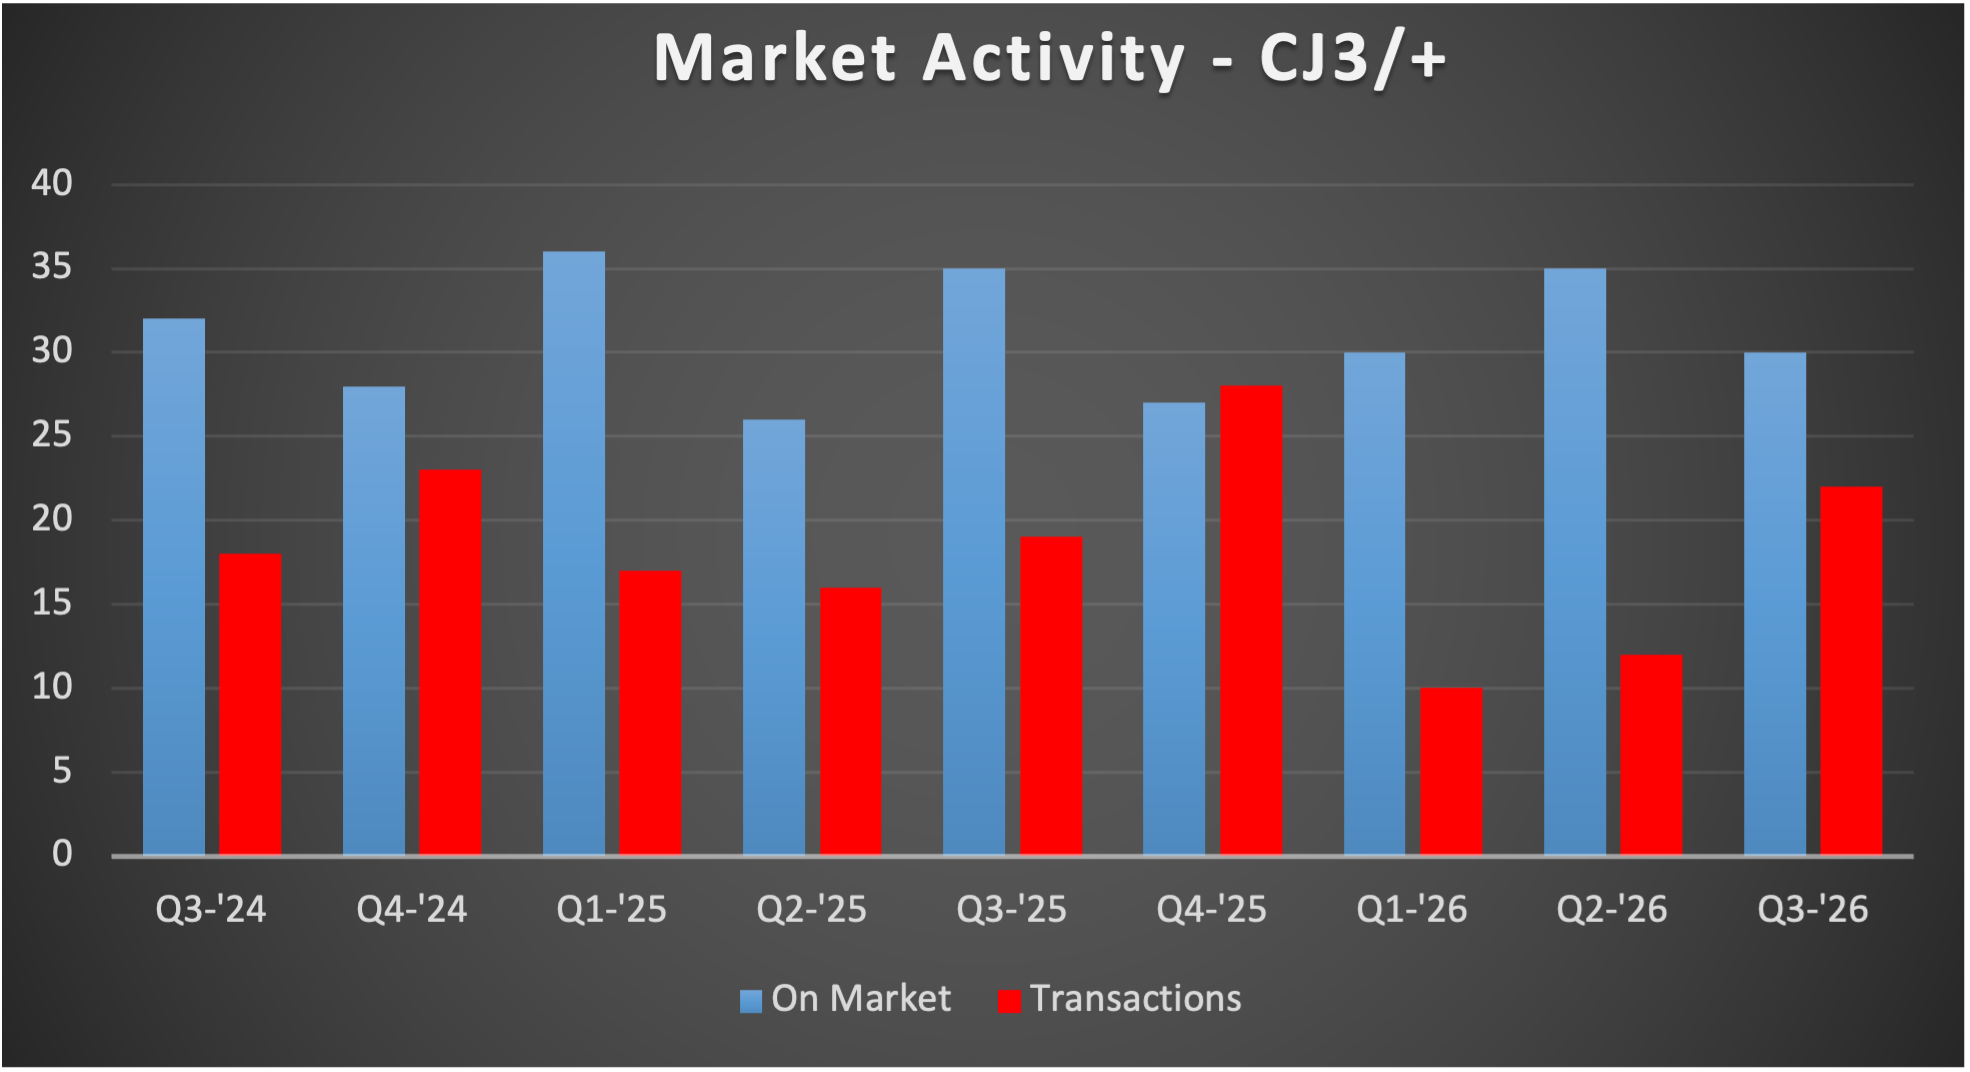
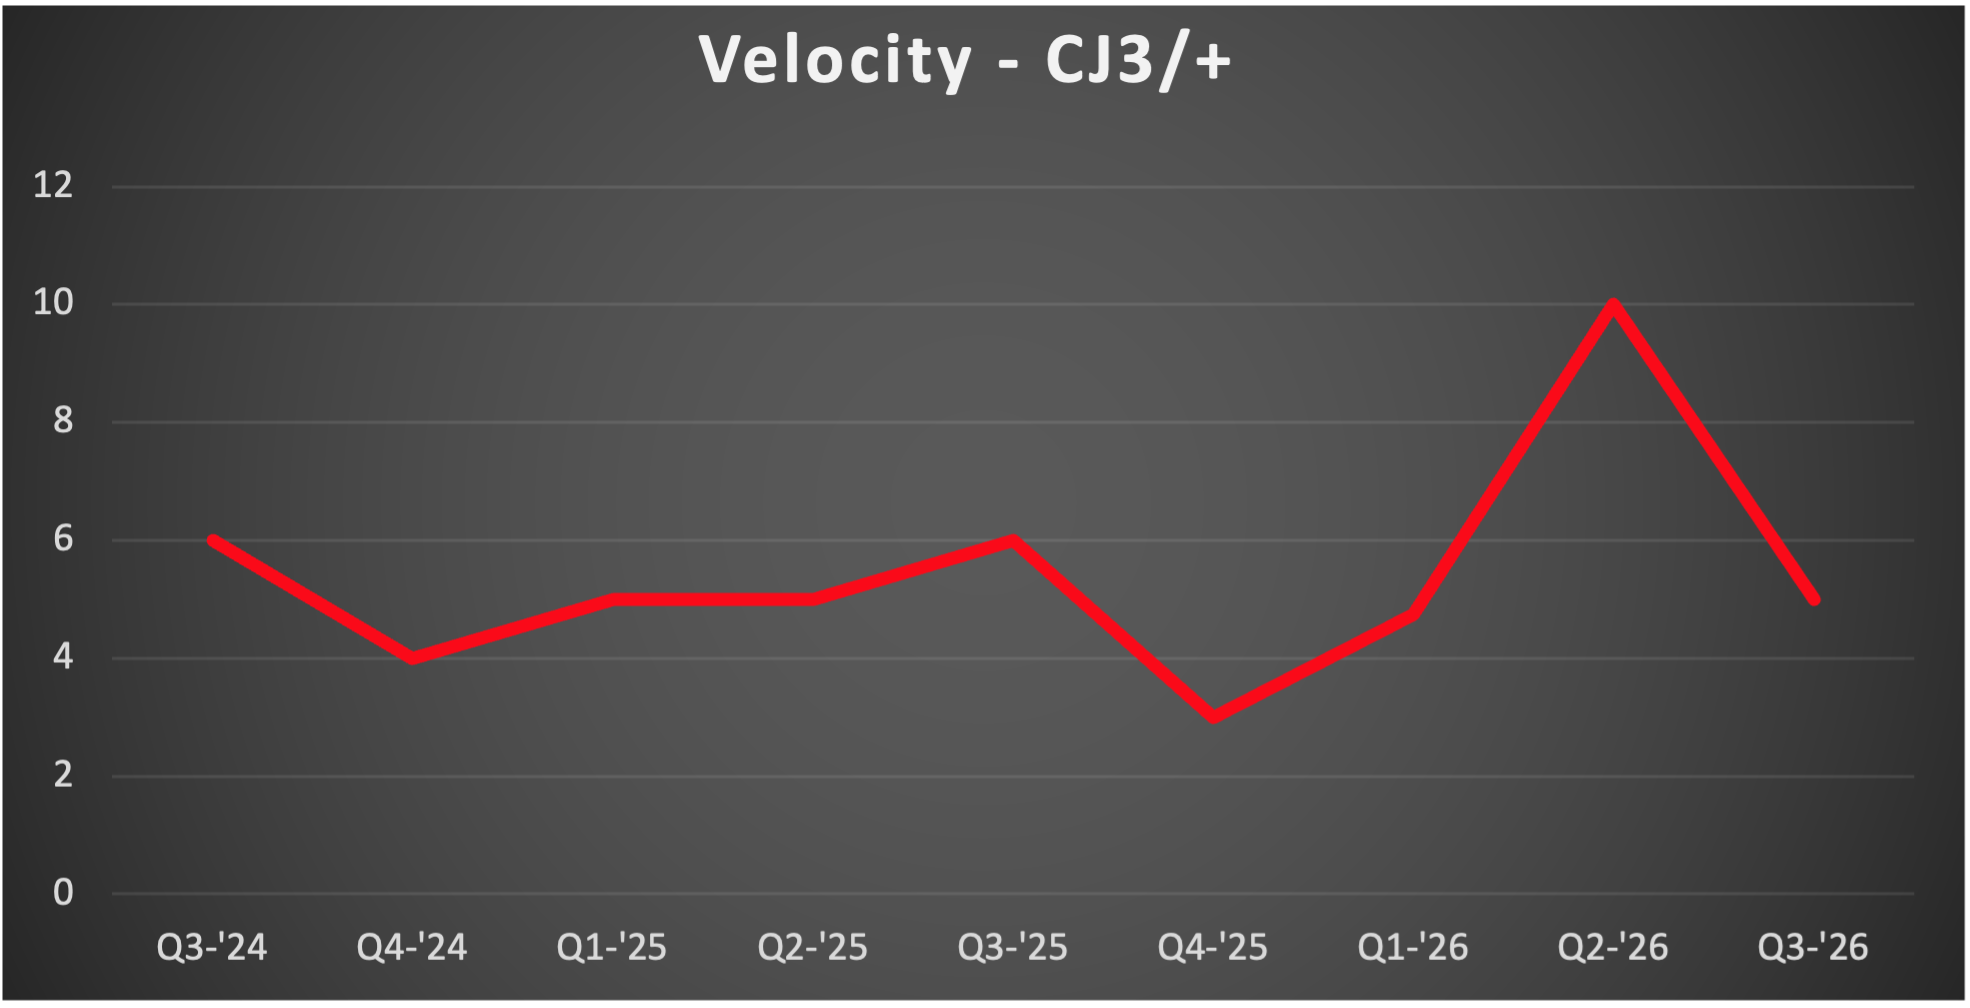
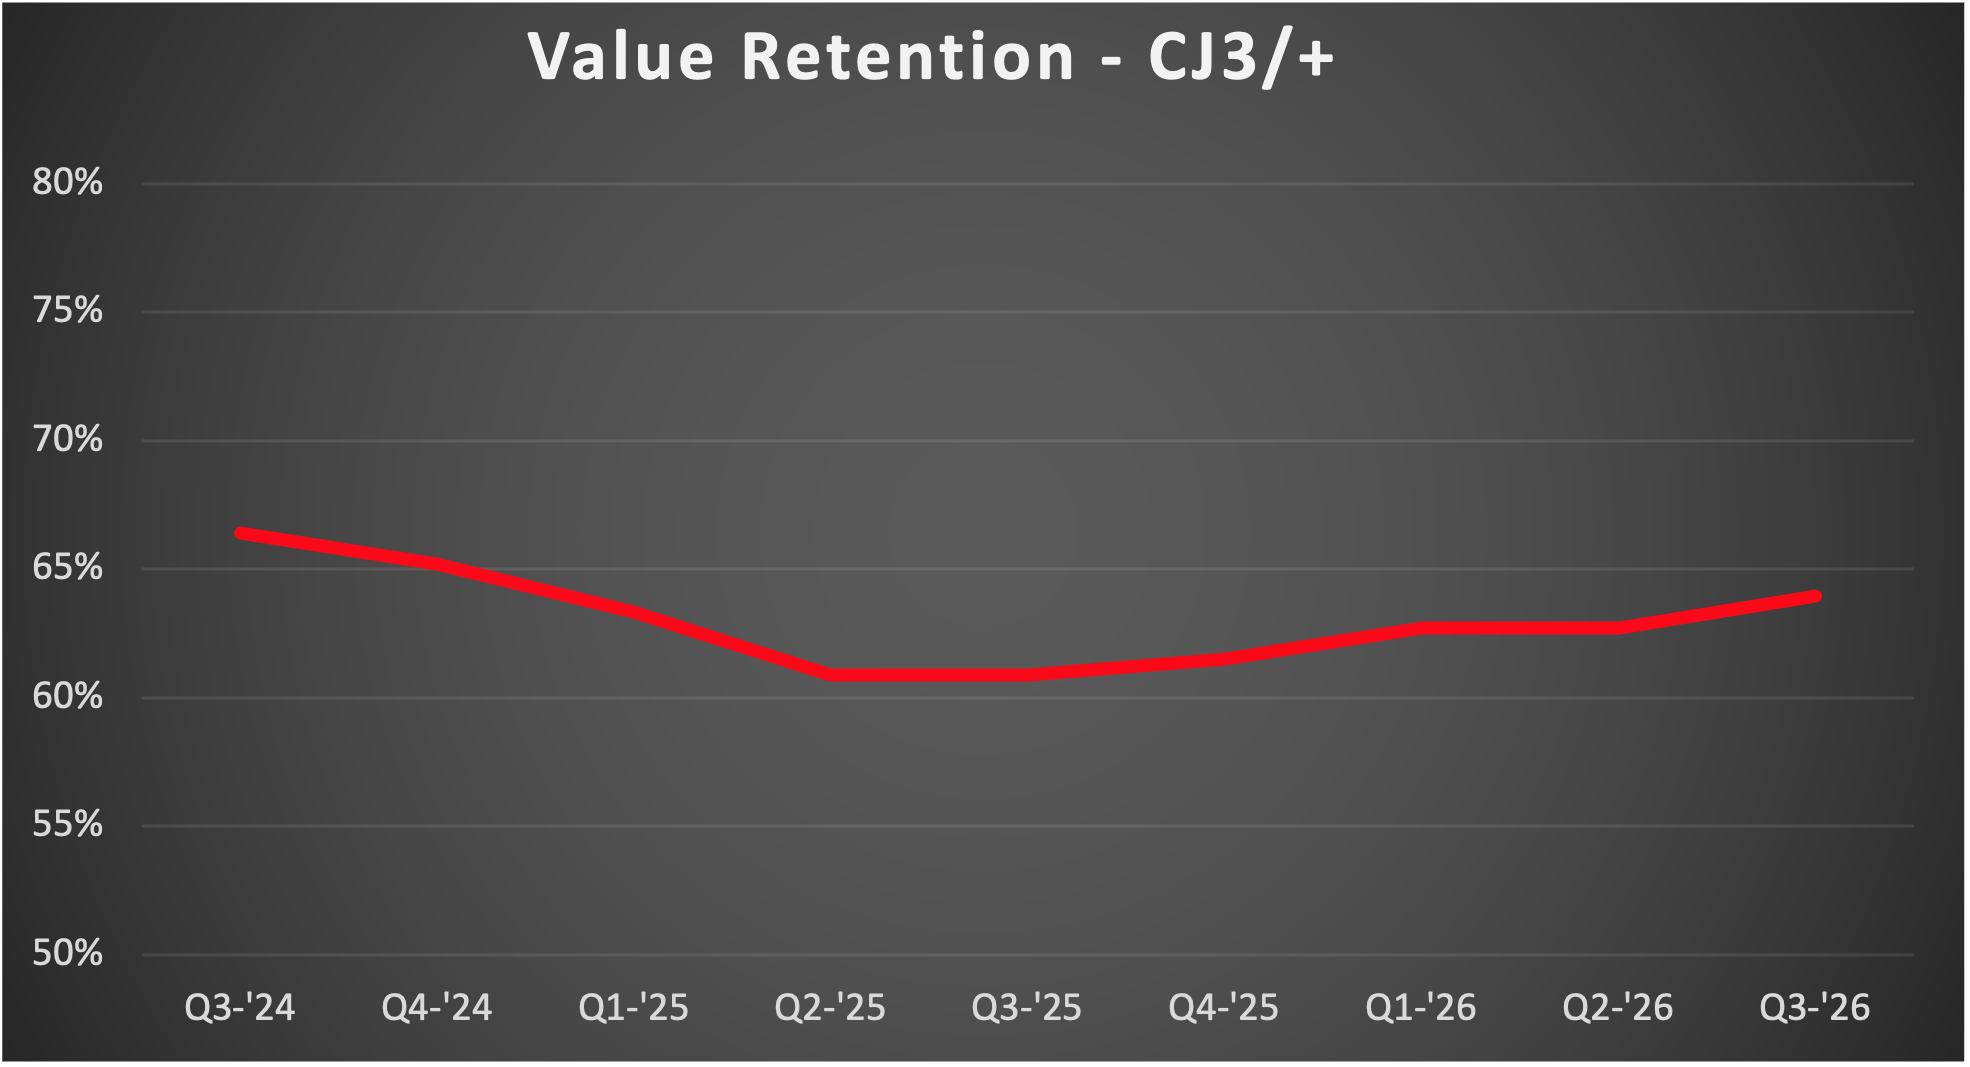
The CJ3 market came back strong in Q3. Transactions nearly doubled from 12 to 22, the most active quarter since Q4 2025, while average inventory fell from 35 to 30 aircraft. Values rose about 2% after holding flat in Q2. Velocity was nearly cut in half, dropping from roughly 10 months to just over 5. The buyer-friendly window flagged in the last two reports has now closed, and the CJ3 market has moved back toward a seller-leaning market heading into Q4, historically the most active quarter for this segment.


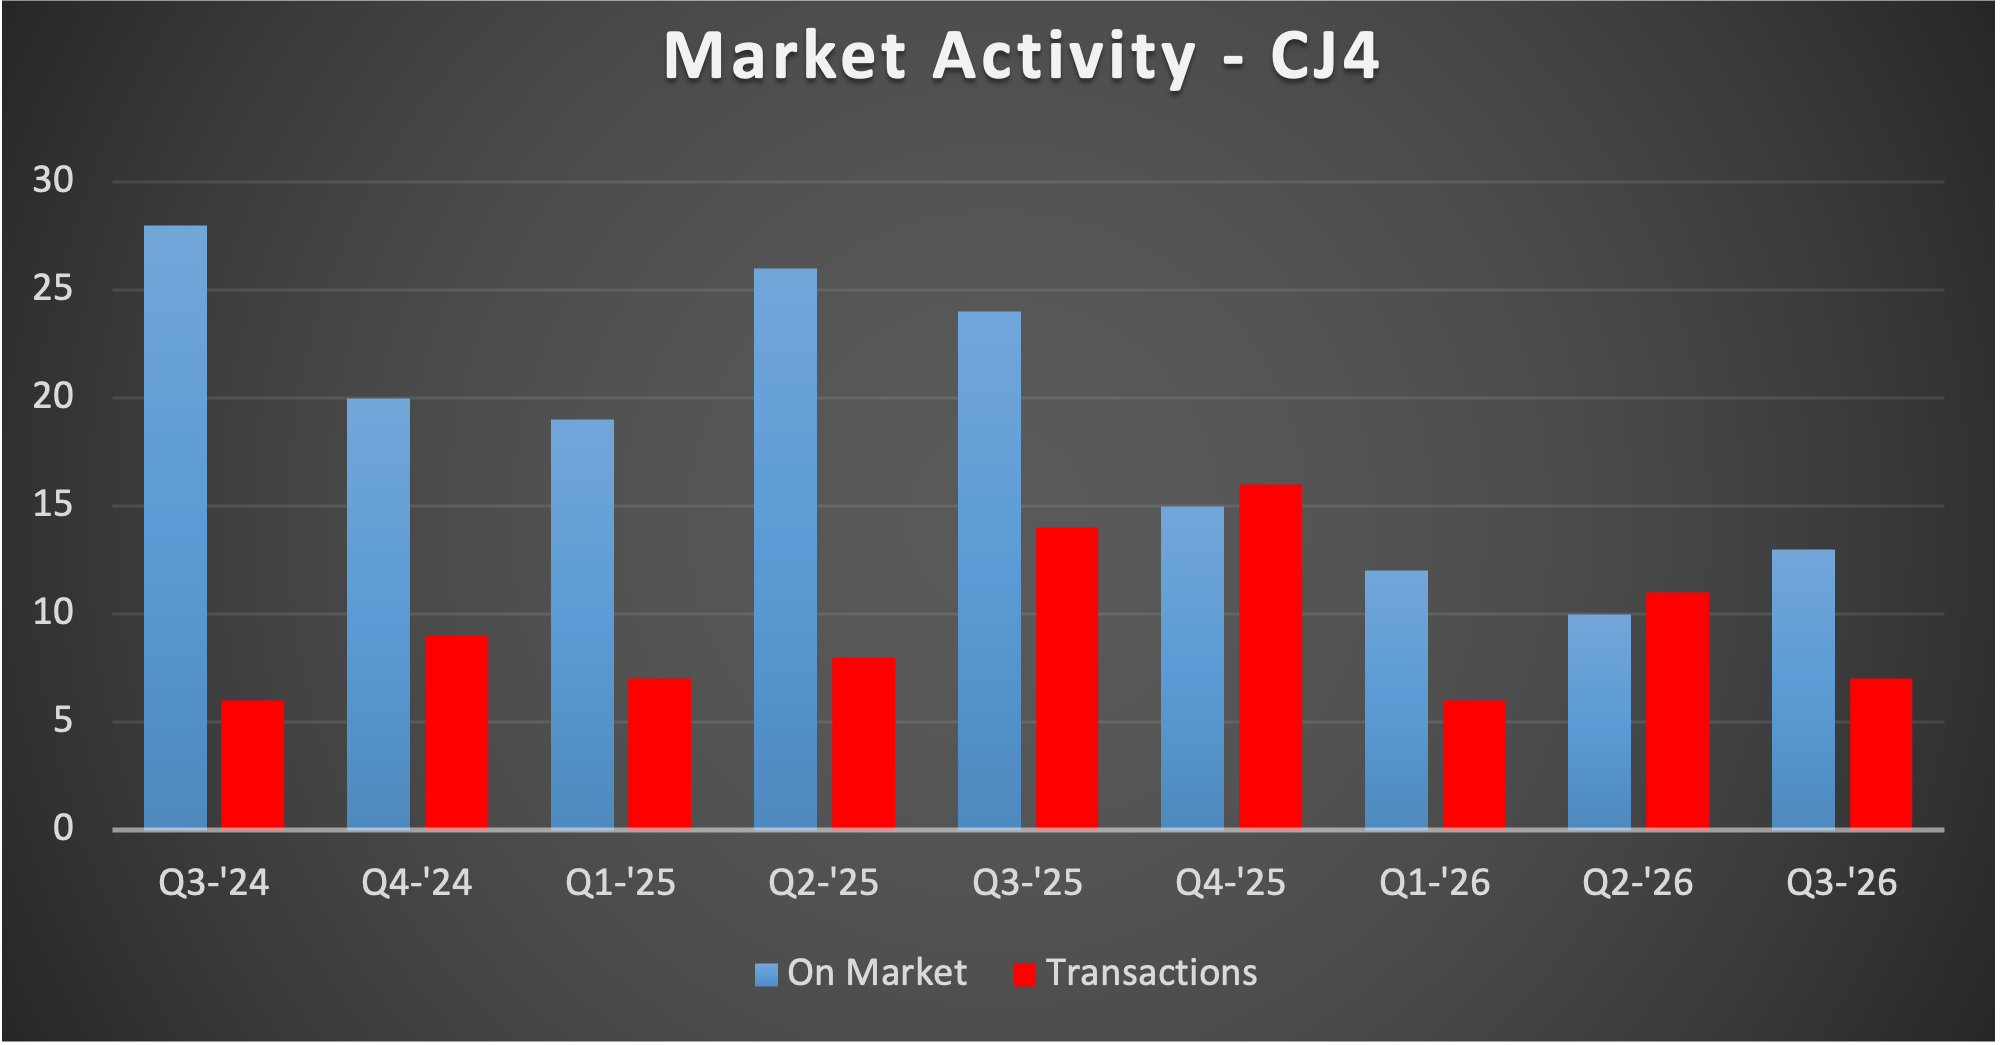
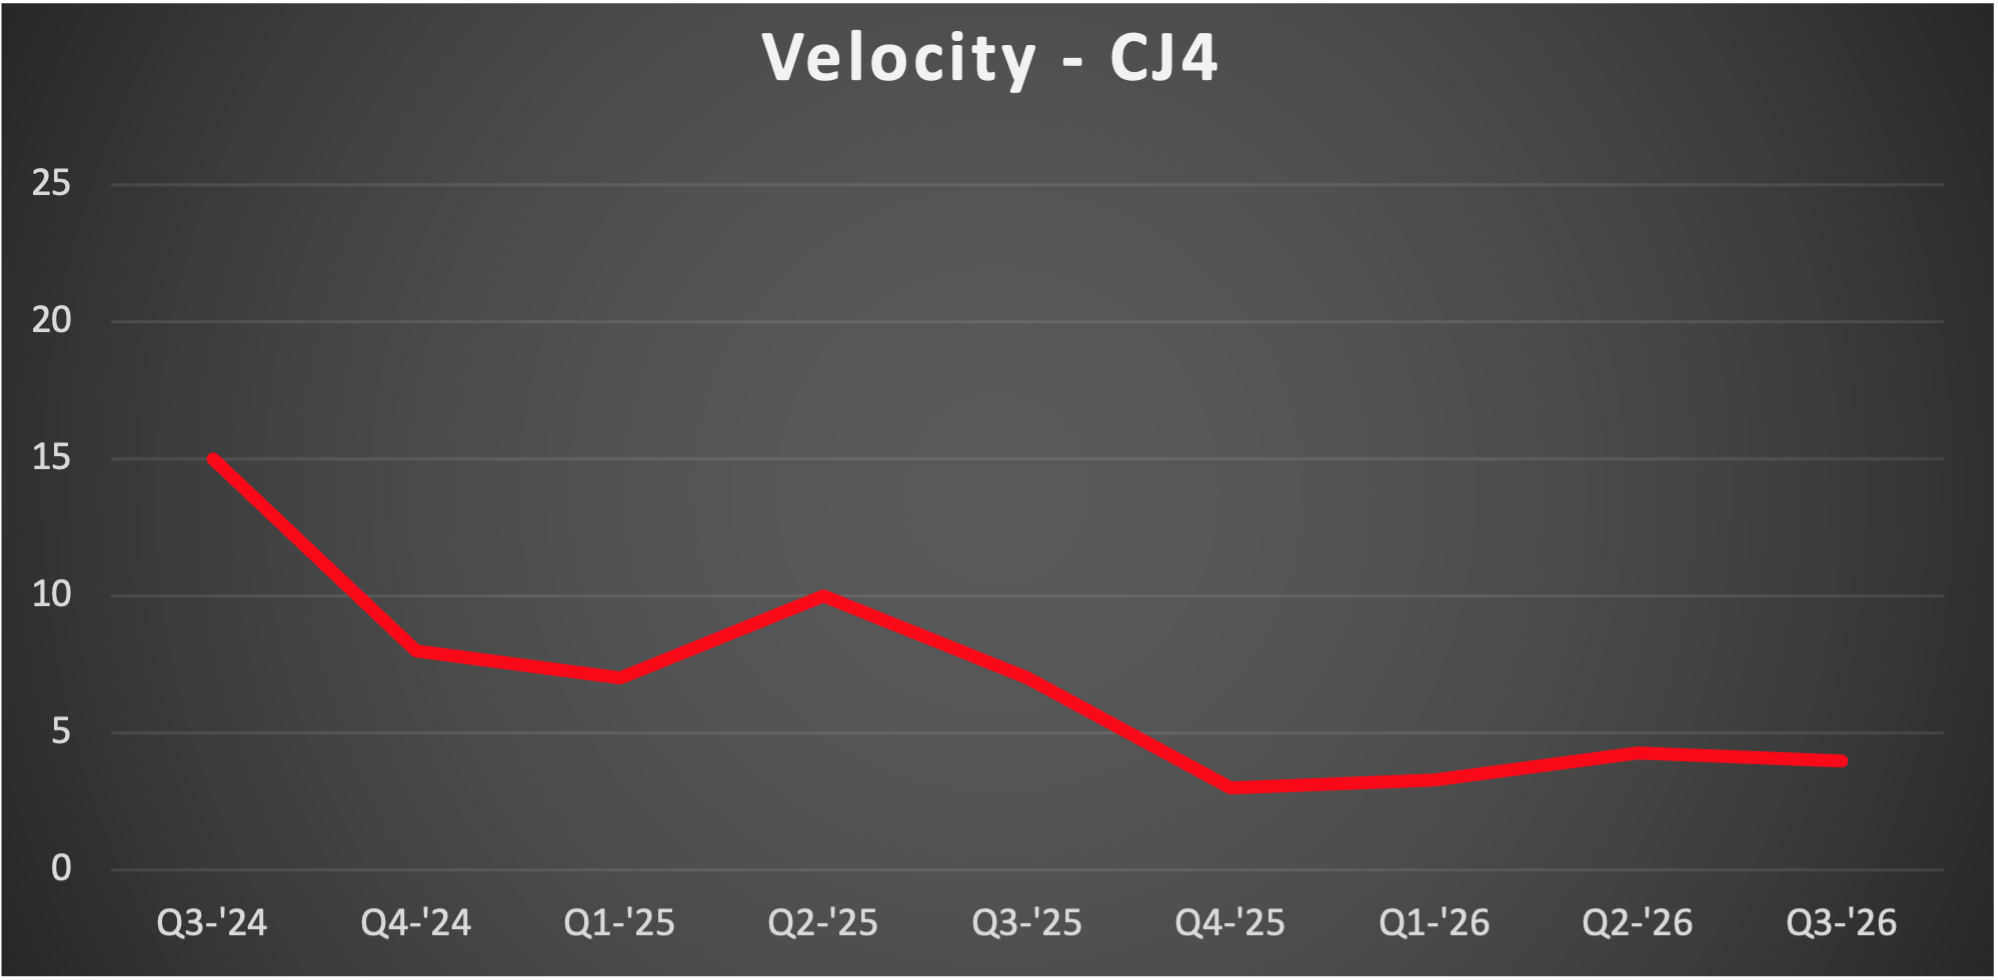
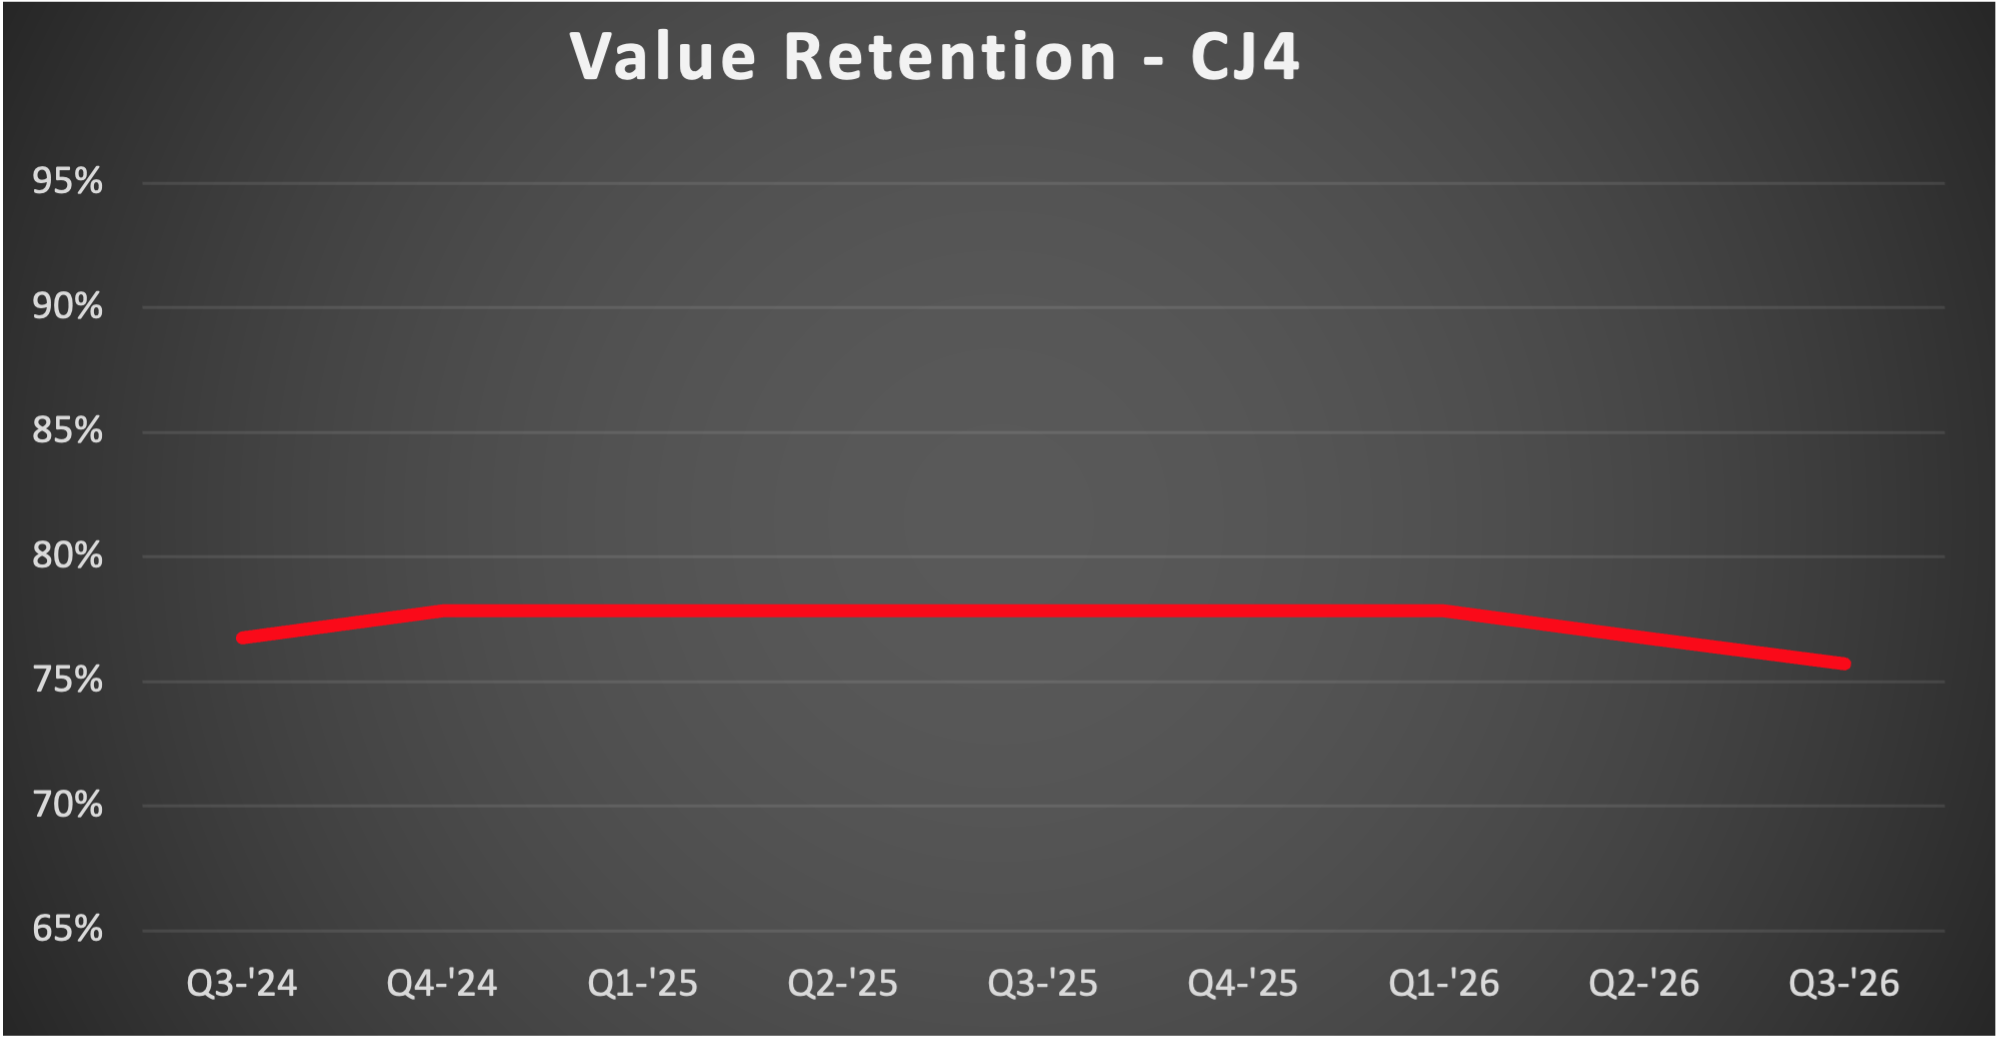
The CJ4 market remains defined by a lack of options. Inventory sits at just 13 aircraft, up slightly from last quarter's record low of 10 but still well below the 24 listed a year ago. Transactions pulled back from 11 to 7, which reflects how few aircraft are available to buy rather than any drop in demand. Values dipped slightly for a second straight quarter, and velocity held just over 4 months. With supply this thin, the CJ4 remains a seller-leaning market, and buyers still need to move quickly whenever a compliant aircraft surfaces.


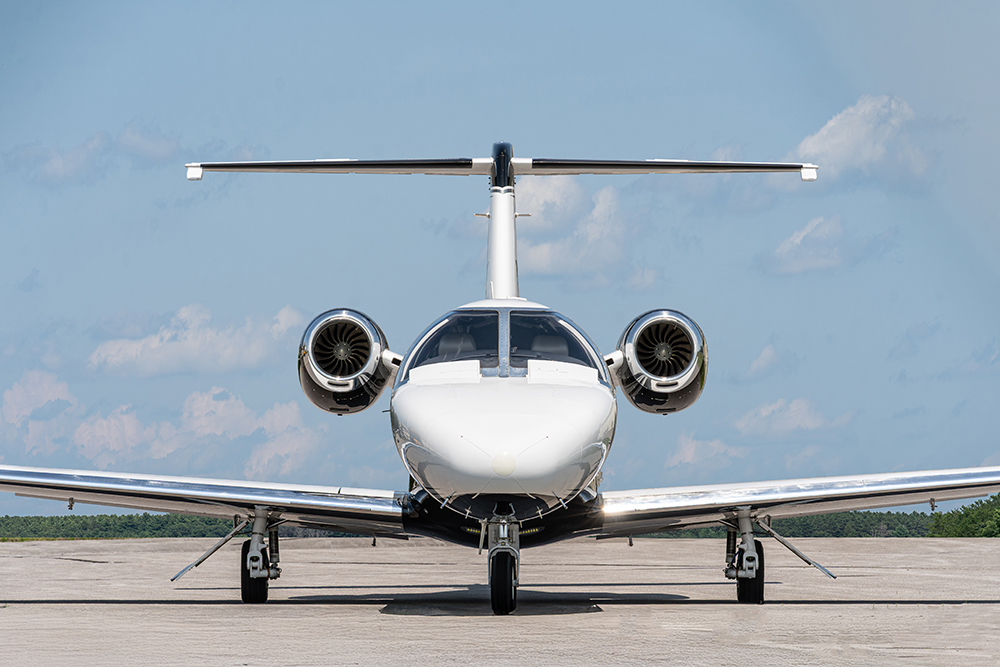
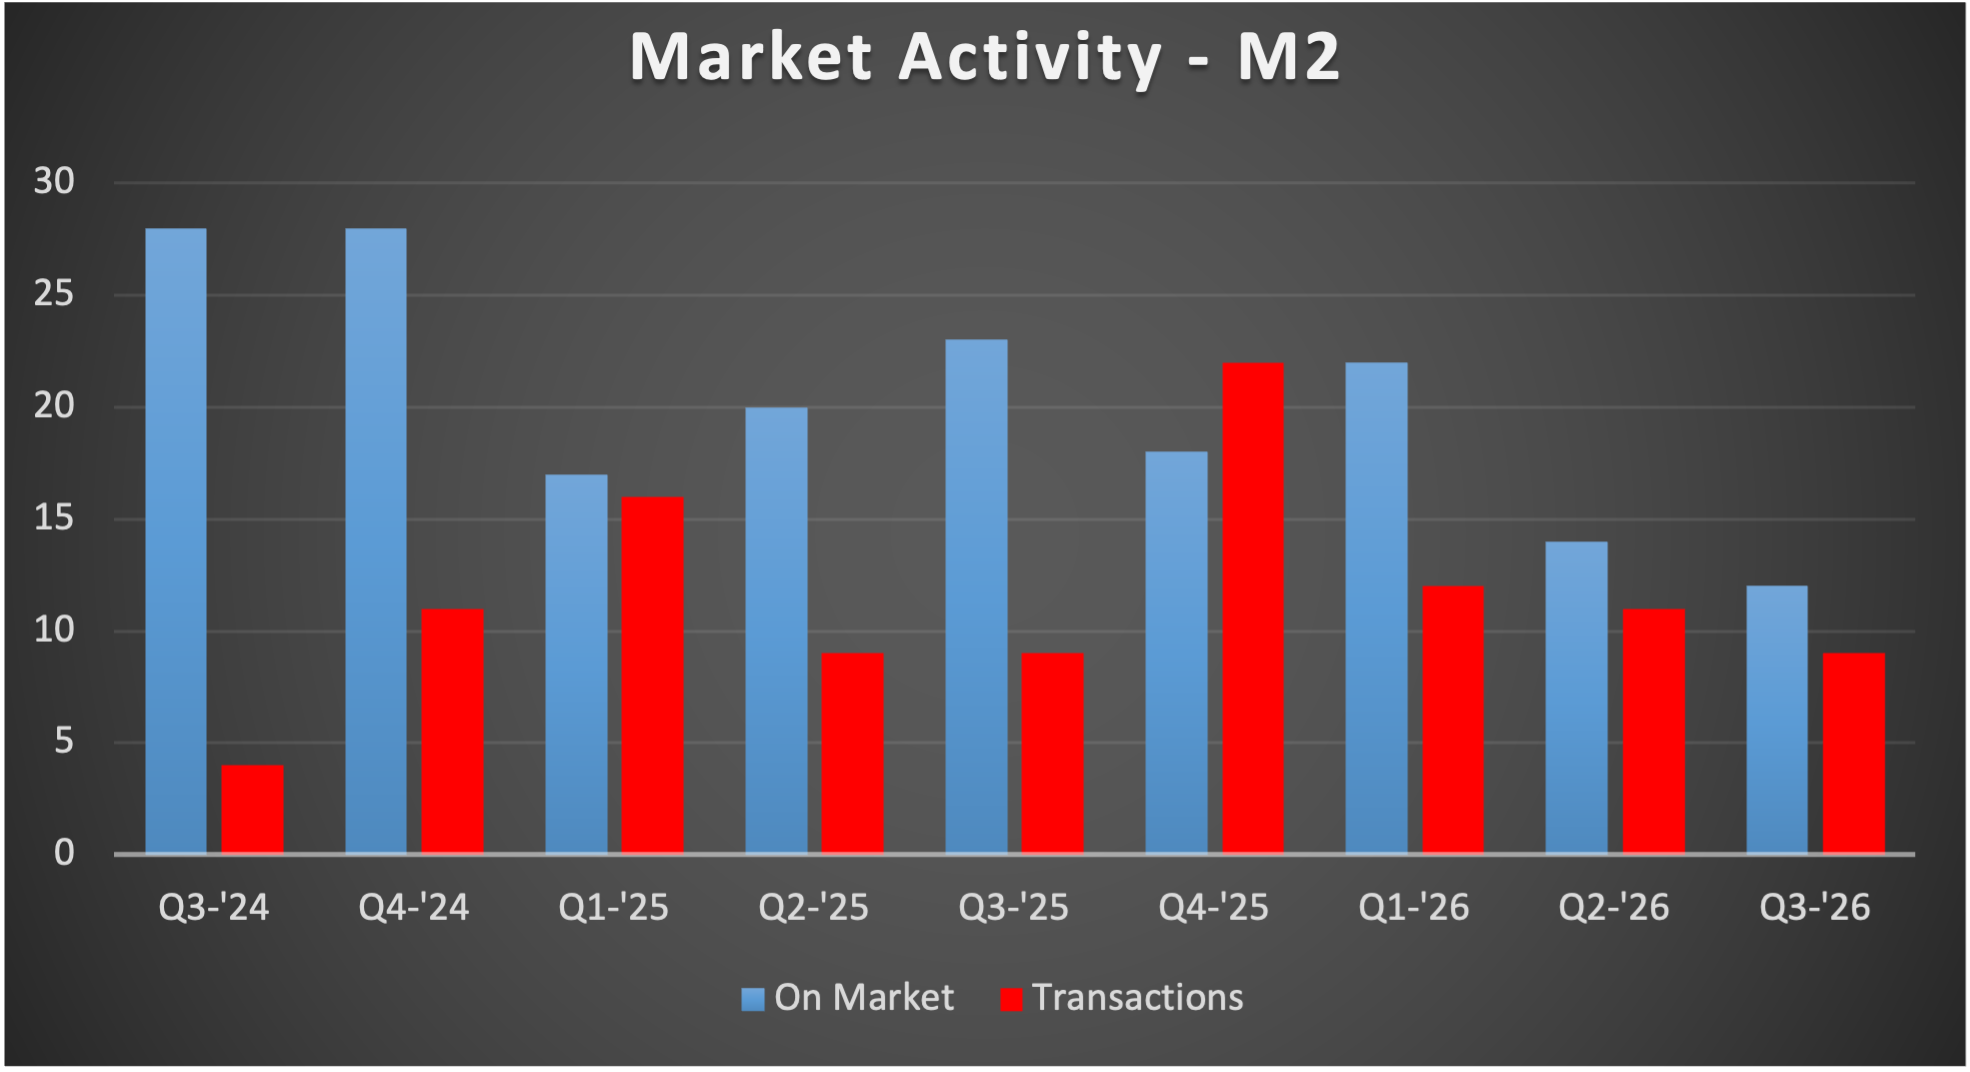
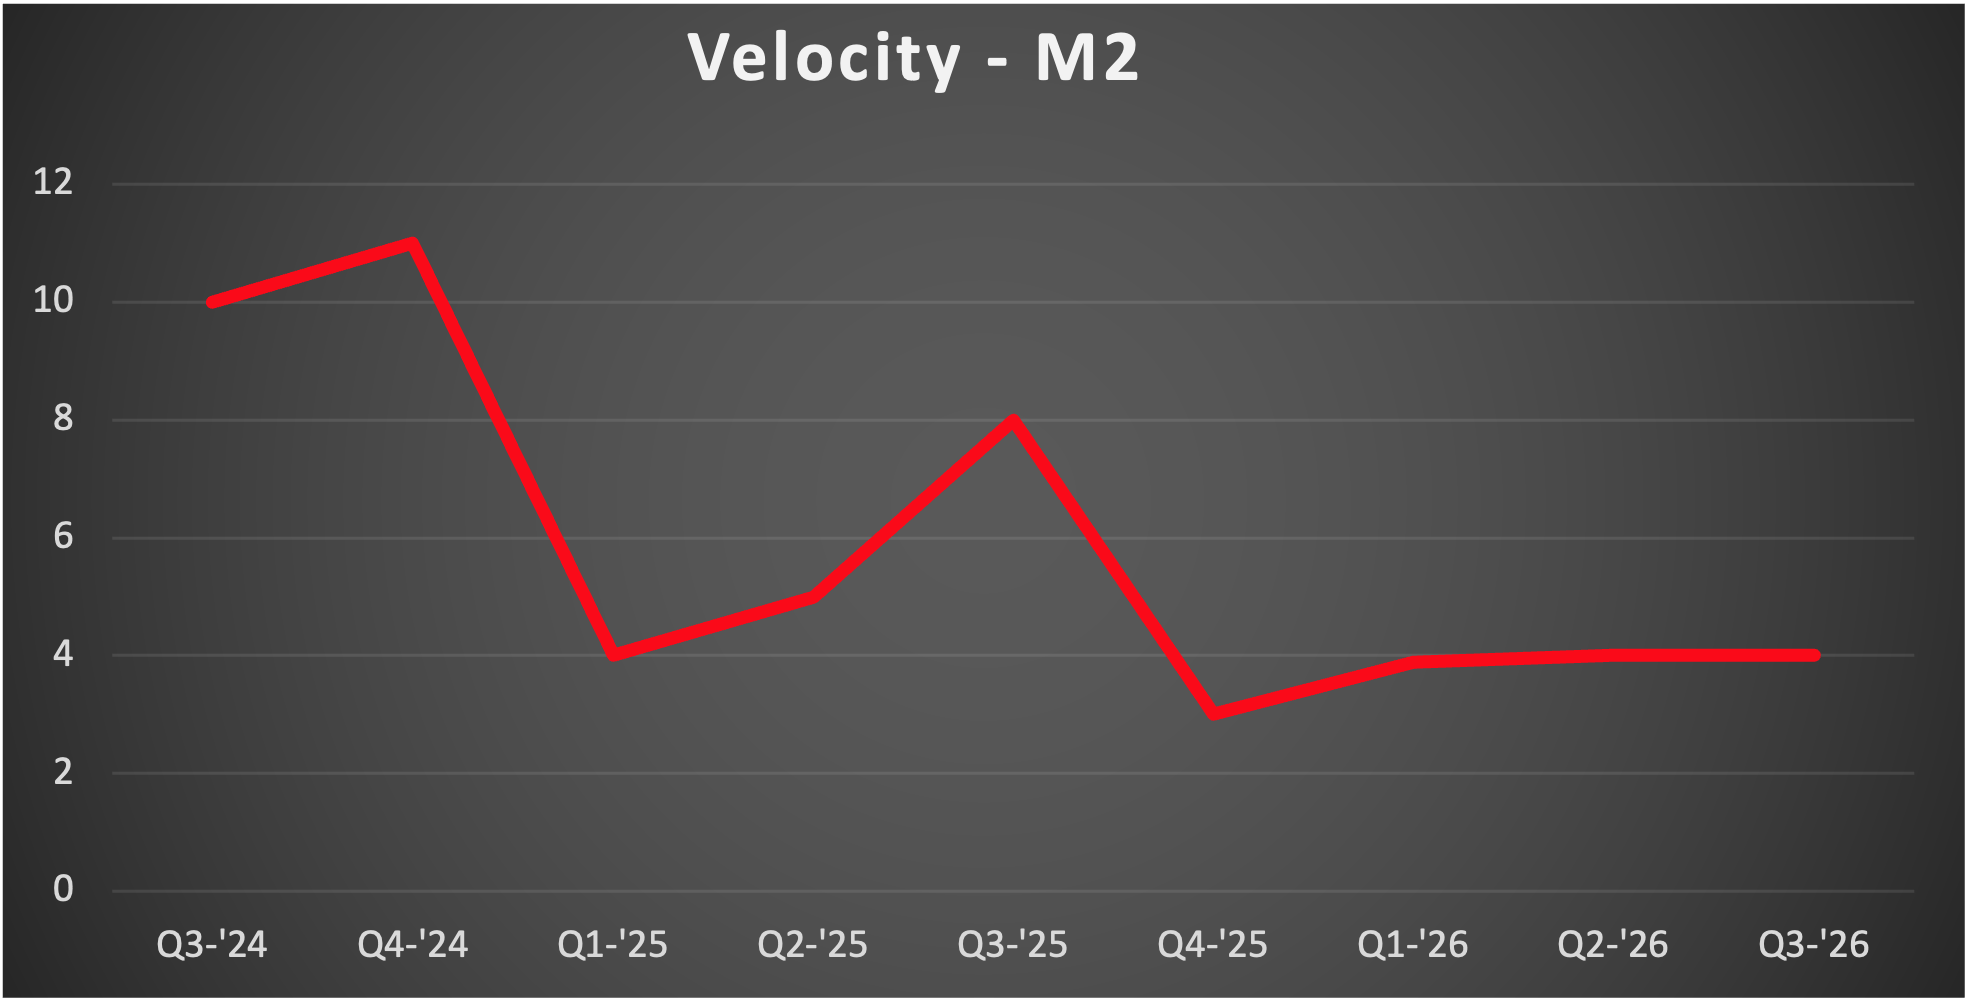
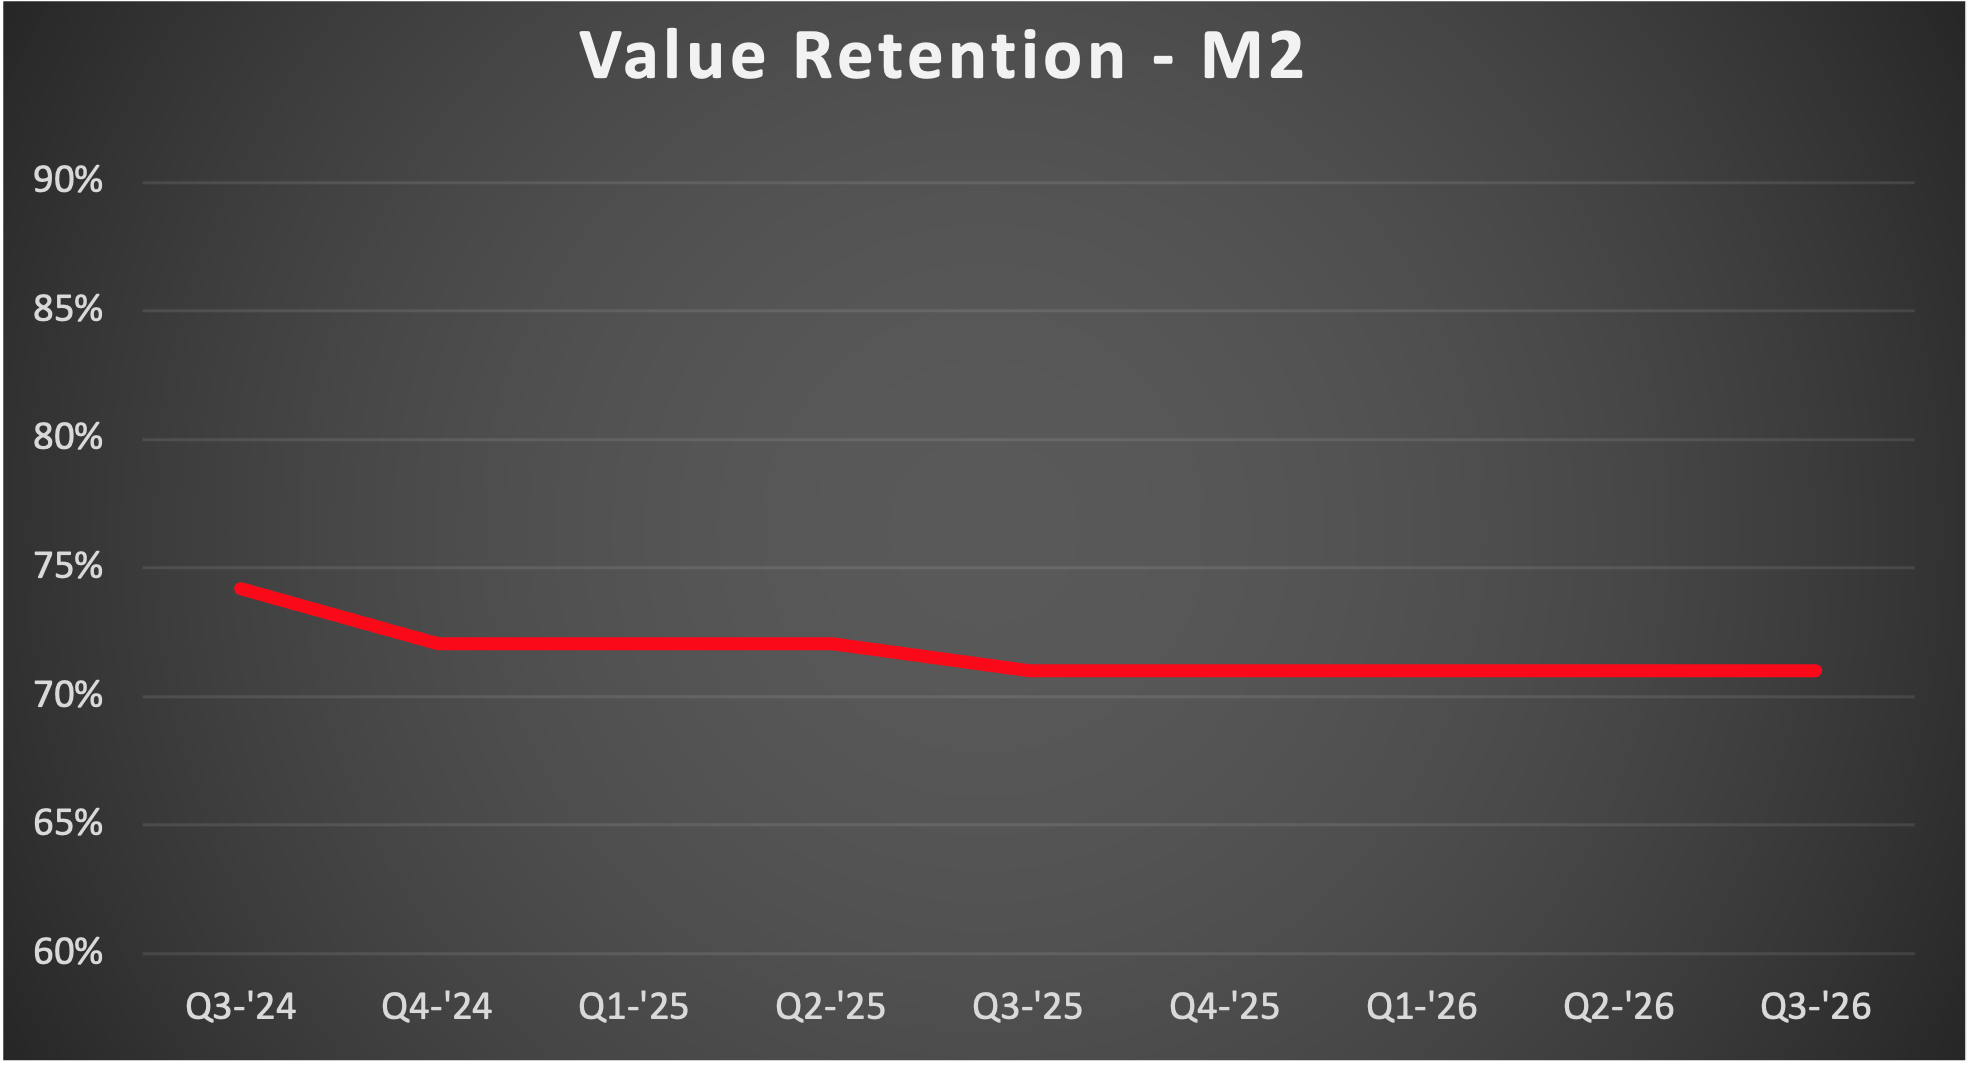
The Citation M2 market continued to tighten in Q3. Average inventory fell from 14 to 12 aircraft, the lowest level in this dataset, while transactions eased from 11 to 9. Values held flat for the fifth consecutive quarter, and velocity was essentially unchanged at roughly 3.6 months. Supply is shrinking faster than demand is cooling, and the M2 market is moving from balanced toward a seller's market, with buyers facing fewer options each quarter.

Our advisory approach combines global market intelligence, discreet representation, and decades of transaction experience to help you move forward with clarity and confidence.